Receivables are the lifeblood of many businesses because they represent money owed by customers. This guide explains how receivables are analyzed, why payment terms matter, and how “Receivables Investopedia” concepts help standardize thinking about liquidity and credit risk. Objective background follows, centered on accounting definitions, risk signals, and common management practices.
Receivables are amounts customers owe a company—often created when goods are delivered or services are performed on credit. In practical terms, they sit between sales and cash collection, turning commercial relationships into measurable liquidity exposure. For readers searching “Receivables Investopedia”, the key idea is consistent: receivables are not cash, and their quality depends on the likelihood and timing of payment.
From an industry perspective, strong receivables management is less about “having invoices” and more about maintaining predictable collection behavior, monitoring credit exposure, and aligning internal processes with accounting rules. When those elements work together, receivables become a controllable asset rather than an unpredictable drain on working capital.
Below, you’ll find a structured, objective analysis of receivables—how to interpret them, how to evaluate risk, and how to manage credit and collection cycles with disciplined controls.
In financial reporting, receivables generally include trade receivables (customer invoices) and, depending on the reporting framework, may also include other short-term amounts due. The important analytical distinction is that receivables represent future cash flows, not current funds. Therefore, their value depends on:
When a company reports higher receivables without a matching improvement in collections, it may indicate slower customer payments, loosened credit standards, or increased sales to less creditworthy customers. Conversely, decreasing receivables could reflect tightening credit and more efficient collections—but it could also signal reduced sales volume or aggressive derecognition practices depending on the accounting and sales model.
This is why receivables should always be interpreted alongside revenue and cash flow. A purely “static” look at the balance sheet (e.g., “receivables up 20%”) can miss whether receivables are high-quality and collectible or whether they are accumulating due to operational frictions, contract disputes, or genuine credit deterioration.
From a systems perspective, receivables are the accounting artifact of operational decisions: sales approvals, delivery confirmation, invoicing accuracy, credit limits, dispute processes, and collection cadence. Because those decisions are controllable, receivables quality can be improved—assuming a company measures the right metrics and manages incentives properly.
Receivables analysis typically focuses on “quality”: the proportion of receivables that are likely to be collected in the normal course of business, and the extent to which past-due items exist. Analysts commonly look for:
While many investors search for “Receivables Investopedia” to understand definitions, professional practice requires going beyond definitions into verification: What collection policies are in place? How is credit risk assessed? Are customer disputes delaying payment? Are disputes increasing? Are invoices being issued promptly after delivery or service completion? Are customers consistently paying within terms—or are they habitually pushing payment later?
Quality also includes composition. Two companies can have the same receivables balance but different risk profiles if one has a diversified customer base with consistent payment histories and the other has a small number of concentrated counterparties where even one problem customer can distort the aging schedule.
Quality analysis is therefore a multi-layered exercise. It examines not only whether customers pay, but how and why they pay late (or don’t pay). Late payments due to billing errors, missing purchase order references, incomplete documentation, or unresolved disputes require different remediation than late payments due to liquidity stress or bankruptcy risk.
Credit risk is transferred to the company when it allows customers to pay later. That credit risk manifests in receivables. An industry expert typically evaluates receivables through both financial statement indicators and operational realities:
In other words, receivables are not merely an accounting category; they reflect the company’s credit discipline and the reliability of its commercial operations. Credit risk is not only about “bad customers.” It is also about predictable operational friction—such as inconsistent billing or frequent service-delivery disputes—that can delay cash even when customers remain willing to pay.
This is why receivables should be viewed as a credit risk pipeline rather than a one-time snapshot. Every invoice moves through a pipeline: creation → delivery/service verification → invoicing → dispute monitoring → collection attempts → cash receipt → write-off (if applicable). Failures at any stage can increase past-due balances.
Even when receivables are “performing,” they still determine how much cash the business has available in the near term. Cash planning becomes more precise when receivables are managed actively, because collection schedules can be forecasted. However, if receivables grow faster than sales are collecting, cash can tighten even as revenue looks healthy.
This is why analysts often compare working capital changes—particularly the net impact of receivables movements on operating cash flow. Reliable interpretation requires aligning the timing differences between:
To ground this in widely accepted guidance, financial reporting frameworks emphasize that receivables should be measured net of expected credit losses or through appropriate valuation allowances, depending on the applicable rules. For readers trying to reconcile “what receivables should be worth,” this is the bridge between accounting and credit risk.
It’s also why the quality of earnings can be tested through cash conversion. A company may show strong revenue recognition yet exhibit weak operating cash flow if receivables are taking longer to convert into cash. That mismatch can indicate genuine credit risk—or it can indicate operational timing issues such as delayed invoicing, ineffective collection, or a shift in customer terms.
Because liquidity is time-sensitive, companies often forecast cash receipts using both historical collection patterns and forward-looking assumptions. Those assumptions include expected payment behavior by customer segment, the proportion of disputed invoices, seasonal patterns, and the expected timing of settlements.
Receivables are not inherently good or bad; their risk is determined by how they behave over time. A helpful way to think about “good” versus “risky” receivables is to distinguish between:
Structural liquidity delays may increase DSO but may not necessarily require large allowance increases if the historical pattern shows eventual collection. Credit deterioration, by contrast, increases the likelihood of write-offs and should influence allowances/expected credit losses under the relevant accounting standard. Operational delays can often be improved quickly with better billing processes, faster dispute resolution, and improved documentation and delivery confirmation.
The challenge is that financial statements rarely label the root cause of late payment directly. Analysts infer it using a combination of aging trends, allowance movements, charge-offs, cash flow reconciliation, and footnote disclosures about credit risk and customer concentration.
Companies often work with suppliers, distributors, and intermediaries, and these relationships influence receivables indirectly—especially when the firm is part of a supply chain. For example, when a company has strict supply lead times or material constraints, it may prioritize orders from customers likely to pay reliably. That selection behavior can improve receivables quality over time.
However, it is important not to assume supplier “pricing” or “terms” without verified documentation. In professional analysis, “supplier details” should be treated as operational variables that can affect customer fulfillment speed, invoicing accuracy, and the frequency of billing disputes—each of which can change receivables outcomes.
If you are evaluating a specific business, the very credible approach is to review internal credit policy documentation, collection KPIs, invoice aging trends, and evidence of dispute handling. External investors typically have limited access to these, so they infer quality through statement data and footnote disclosures.
For example, if a company’s customer disputes increase—particularly disputes related to delivery dates, quantities, service performance, or billing documentation—this is a plausible driver of rising past-due receivables. But it still should be treated as an inference until corroborated by disclosed risk factors, management discussion, or other narrative in filings.
Similarly, if delivery performance becomes inconsistent due to operational constraints, invoices may be delayed or corrected, which can distort DSO metrics and temporarily increase receivables. A disciplined analyst separates these operational drivers from credit deterioration by comparing patterns: Is the aging older due to disputes? Do charge-offs rise? Does the allowance increase? Do customers who dispute eventually pay once resolved?
Below are common analytical angles used by finance professionals to evaluate receivables. In practice, you seldom rely on one metric alone; you triangulate.
Receivables turnover reflects how efficiently a company collects. DSO provides the average number of days it takes to collect cash from customers. If DSO rises while revenue growth remains flat or weak, analysts often view that as a potential collections problem.
DSO should be interpreted in the context of the business model. For example, subscription businesses may have different invoicing cadences than project-based services. A B2B manufacturer selling with net-60 terms will naturally have a different baseline DSO than a business selling net-15 terms. Therefore, DSO comparisons are best done:
Also, note that DSO calculations can be sensitive to how revenue and average receivables are measured. Analysts should be mindful of whether revenue used is gross or net, and whether receivables include allowances netted or gross amounts with separate allowances.
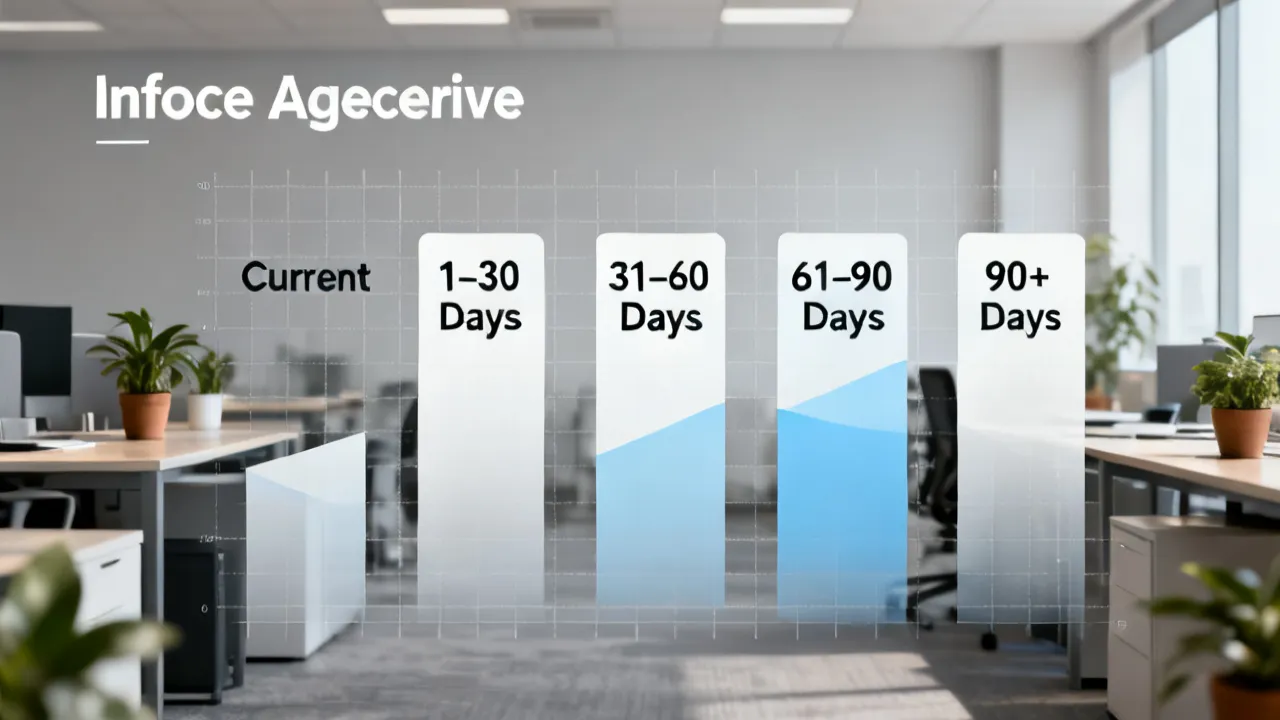
An aging schedule separates receivables by how long they have been outstanding (e.g., current, 30–60 days past due, 60–90 days past due, and beyond). A heavy tail in older buckets can indicate either customer distress or systemic issues like delayed invoicing and dispute backlogs.
Aging schedules are often the single most actionable disclosure for credit analysis. They show whether risk is spreading broadly (many accounts modestly late) or concentrated in older buckets (few accounts becoming increasingly overdue). The shape of the aging distribution can hint at the underlying cause:
In internal management, aging is complemented with account-level data: who is past due, for how long, and whether there are disputes. External investors usually cannot see account-level details, so they rely on aggregated aging metrics and narrative disclosures.
Allowance disclosures can reveal how management estimates expected credit losses. A rising allowance relative to receivables may signal worsening credit conditions, changes in risk models, or a shift in customer mix. Conversely, a declining allowance could mean improved collection performance or—less favorably—more aggressive estimation assumptions.
The professional question is always: “What changed, and is the change consistent with observed payment behavior?” If DSO increases and aging worsens while allowance decreases, that mismatch can indicate estimation lag or potential under-reserving. However, it could also reflect changes in accounting methodology or better data about expected credit losses. Therefore, allowances must be analyzed alongside operational indicators.
Modern accounting frameworks generally require allowances/expected credit losses to incorporate reasonable and supportable information, including forward-looking factors where applicable. That means analysts should look for disclosures that explain:
In receivables analysis, “allowance coverage” is a useful lens. Coverage is typically interpreted as allowance divided by gross receivables (or by some measure consistent with disclosed allowance basis). Coverage trends can help detect deterioration even before cash collections visibly decline.
Charge-offs reflect amounts deemed uncollectible and removed from the receivables balance. They are critical because they validate that some receivables were not recovered. Analysts should review charge-off trends relative to:
Charge-offs are also impacted by legal and procedural factors. A company may pursue collections diligently, delaying write-offs, which can keep charge-offs low while disputes and past-due balances accumulate. Therefore, charge-offs must be interpreted alongside aging and dispute processes.
Operating cash flow is the ultimate test. If operating cash flow is persistently weak while receivables remain stable, there may be other working capital drags (inventory, payables). If receivables increase while cash flow weakens, receivables are likely a major driver.
If cash flow is weak because receivables are growing, analysts often look for the direction of the working capital movement and the relationship to revenue timing. For example:
Cash flow reconciliation helps separate accounting timing effects from collection performance. Although revenue recognition and cash receipts are inherently different, sustained misalignment can reveal a credit discipline gap.
Many receivables issues are “collection timing” rather than “credit inability.” Disputes can be delayed settlements, back-and-forth approval processes, or documentation mismatches. Even if accounting standards require recognizing revenue at delivery and creating receivables, dispute handling determines how quickly invoices convert to cash.
Internally, dispute management metrics include:
External disclosures may not provide all these metrics, but investors can sometimes detect dispute-related issues through narrative discussion, changes in allowance assumptions, or sudden shifts in working capital behavior.
Customer concentration can distort receivables risk and create fragility. If a small number of customers represent a large portion of receivables, then:
For credit risk analysis, concentration also influences governance. A company with concentrated receivables should have robust credit review processes, active account monitoring, and strong documentation practices.
Receivables management becomes more reliable when the organization meets a set of operational and control prerequisites. These conditions are not merely “nice to have”—they reduce estimation errors, prevent leakage, and strengthen predictability.
Instead of guessing, finance teams typically formalize requirements for credit approval, invoicing accuracy, dispute escalation, and collection governance. When those requirements are not met, receivables quality deteriorates—often without immediate recognition in cash flow.
The “robustness” of receivables management can be evaluated by asking operational questions that link process to outcomes:
Robust management also includes governance: clear separation of duties between sales creation, billing execution, credit approval, dispute handling, and financial reporting. Without governance, incentives can conflict (e.g., sales teams favor approvals and recognition; finance must ensure credit risk is accurately reflected).
Below is a practical approach finance teams often follow. It can be adapted to different business models (B2B services, distribution, manufacturing, subscriptions with invoicing, and more).
This workflow emphasizes that receivables management is not purely a collections function. It is a cross-functional system requiring coordination between sales, operations, billing, customer service, legal/contract teams, and finance.
The table below contrasts common receivables signals with actions and the conditions under which those actions are appropriate.
| Signal observed in receivables | What it may indicate (objective interpretation) | Typical action by finance teams | Conditions/requirements to proceed |
|---|---|---|---|
| DSO increases for multiple periods | Collections slowdown, stricter dispute patterns, or customer credit deterioration | Review collection cadence, escalate disputes faster, reassess credit limits | Confirm invoice accuracy; verify dispute volume trends; review customer payment history |
| Higher past-due concentration in aging buckets | Risk concentration or procedural delays in billing/collection | Implement targeted outreach; assign accounts by risk tier | Maintain accurate aging data; ensure contact and escalation procedures exist |
| Allowance for credit losses rises relative to receivables | Updated expectations of non-payment or changes in customer mix | Validate underlying models/assumptions; align with payment evidence | Document evidence; follow applicable accounting policies; ensure governance over estimates |
| Operating cash flow lags while receivables rise | Receivables not converting into cash as expected | Reforecast cash collections; adjust working capital assumptions; evaluate financing options if needed | Assess whether delays are temporary (e.g., disputes) or structural (e.g., credit risk) |
| Receivables stable but customer disputes increase | Cash timing issues due to contract interpretation rather than inability to pay | Improve dispute resolution workflow; strengthen documentation to support billing | Ensure legal/contract review capability; maintain evidence for invoices and delivery/service proof |
| Charge-offs increase | Credit deterioration or inability to collect disputed balances | Reassess customer risk and collection strategies; adjust credit limits; update allowance estimates | Confirm write-off approvals per policy; review recovery attempts and legal outcomes |
| Top customers represent increasing share of receivables | Higher concentration risk; potential fragility in liquidity | Increase monitoring frequency; consider credit enhancement or tighter terms where appropriate | Verify concentration calculations; ensure credit governance and contract enforceability |
Because “Receivables Investopedia” often points readers toward general definitions, it’s useful to anchor interpretations in established frameworks. The following institutions provide baseline guidance on credit loss recognition and measurement concepts used across modern accounting standards:
For general concepts and definitions, Investopedia-style educational explainers typically summarize these frameworks, but professional analysis should always prioritize primary accounting standards and issuer disclosures. In particular, issuer disclosures clarify which receivables are subject to which credit risk models and whether the allowance is computed on a collective basis (by aging) or on an individual basis (for large or impaired accounts).
Accounting frameworks also influence presentation: whether receivables are shown gross with an allowance in a contra account, or presented net, and how expected credit losses are recorded. These presentation differences can affect comparability if analysts are not careful.
Receivables are amounts owed to a company by customers or counterparties for goods delivered or services provided on credit. They are reported as an asset, but their value depends on collectability and timing of payment.
Educational sources often clarify basic definitions and the relationship between sales, accounting recognition, and cash collection. However, investors should validate the concept with the company’s actual disclosures—especially aging schedules and allowance/expected credit loss methodologies.
No. Receivables can rise due to legitimate sales growth or expansion into new markets. The professional question is whether receivables are converting into cash at a rate consistent with the company’s historical collection patterns and credit policy.
DSO (days sales outstanding) estimates the average time to collect cash from customers. Rising DSO often signals collections problems, customer credit issues, or operational bottlenecks such as invoicing errors or disputes.
It represents management’s estimate of expected non-payment (based on the relevant accounting framework). It acts as a valuation measure for receivables, reflecting both past experience and reasonable, supportable expectations.
Disputes can delay payments even when customers are ultimately willing to pay. A mature process tracks disputes, resolves them quickly, documents evidence, and escalates appropriately—so the company distinguishes “delayed” from “unlikely to collect.”
Strong credit management typically requires clear credit approval policies, accurate invoicing, consistent payment term enforcement, aging-based collection workflows, documented dispute handling, and governance over credit loss estimates.
Yes. Many improvements come from operational refinements—invoice accuracy, faster escalation, improved customer communication, tighter credit limit reviews, and better reporting cadence for collections and disputes.
Supplier relationships can influence fulfillment timelines and operational reliability. If fulfillment delays increase or product/service delivery proof becomes inconsistent, invoicing disputes may rise, which can affect receivables aging and cash timing. The relationship is indirect but meaningful.
They start by reviewing receivables disclosures (including aging and allowance methodology), then assess trends in DSO and working capital movements, and finally reconcile these with operating cash flow and operational indicators like dispute volume and billing accuracy.
A practical approach is to combine three lines of evidence: (1) whether aging is worsening primarily due to older buckets, (2) whether allowance and charge-offs move in a way consistent with worsening credit risk, and (3) whether cash collections improve after disputes or billing issues are resolved. When timing differences drive receivables growth, operating cash flow often improves after process issues are fixed, and allowance/charge-offs may not rise sharply.
Contract terms define payment timing, dispute windows, acceptable documentation, and remedies for non-payment. Changes in terms—such as extended payment schedules, looser documentation requirements, or shorter dispute resolution timelines—can affect how quickly invoices become collectable and therefore how receivables behave.
It can. Legal action may be part of escalation for chronically non-paying accounts. However, effective receivables management typically uses legal resources selectively and only after establishing documentation, dispute clarity, and procedural compliance. Premature legal action can be costly and may still not resolve the underlying cause if disputes or documentation gaps remain.
Because allowances/expected credit losses are intended to capture not only already-impaired accounts, but also expected future losses based on risk factors and forward-looking information where required. A company with “current” receivables could still have higher expected losses if its credit quality indicators deteriorate or if macro conditions suggest increased non-payment likelihood.
Receivables financing arrangements can change reported receivables balances and cash flow timing. Depending on the accounting treatment and whether receivables are derecognized, analysts must understand the structure of the arrangement and disclosures about continuing involvement, recourse, and transfer terms. Otherwise, comparing receivables balances across periods may be misleading.
When analyzing receivables in any region described as “nearby” (rather than a specific city or country), the practical takeaway for finance teams remains consistent: collection behavior is shaped by local commercial norms, invoicing conventions, and dispute cultures. In many nearby markets, relationship-driven contracting can lead to informal payment expectations even when written terms exist. That makes aging analysis and dispute tracking especially important, because payment delays may be cultural and operational rather than purely financial inability.
Operational nuance matters: finance teams benefit from aligning sales and billing processes with how customers in nearby markets typically validate invoices, confirm deliveries, and handle service milestones. For example, if customers commonly require additional documentation or prefer a specific invoicing format, failing to meet that expectation can create a predictable dispute backlog—raising past-due receivables without necessarily indicating increased credit default risk.
From an analysis standpoint, “nearby market” dynamics also mean that DSO benchmarks should be adjusted. A DSO of 60 days in one market may be normal, while in another it may be a sign of process failure or increased credit stress. Analysts therefore triangulate using internal targets, peer comparisons with similar market norms, and narrative disclosures about working capital.
Professional evaluation often goes beyond ratios and headlines. The goal is to identify whether receivables are behaving like a stable collection engine or like a warning sign of deteriorating credit.
Here are practical tests finance professionals use:
These tests are particularly valuable when receivables balances rise while management provides limited narrative explanation. They also help distinguish whether management’s allowance estimates are aligned to actual outcomes.
Interpreting receivables can be deceptively challenging. Common pitfalls include:
A disciplined approach uses ratios and narrative together. It considers both the accounting presentation and the operational mechanisms that create the numbers.
Receivables are a central element of working capital and a direct reflection of credit risk, collections discipline, and operational execution. If you approach them using only the “size” of the number, you risk missing deterioration hidden inside aging buckets, dispute queues, or allowance changes. The more professional approach—consistent with how “Receivables Investopedia” education frames the topic—is to connect receivables to collectability, timing, and cash conversion.
When you implement risk-aware credit policies, strong invoicing controls, disciplined collections workflows, and transparent allowance governance, receivables can become a stable asset that supports sustainable liquidity planning rather than an opaque source of cash strain.
Ultimately, receivables analysis is about answering one question: Will the company convert its invoices into cash on a predictable schedule, and is it measuring the risk of non-payment accurately? The answer is visible in the interplay between aging, allowances, charge-offs, dispute behavior, and operating cash flow—together forming the credit-risk “signal” behind the accounting line item.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
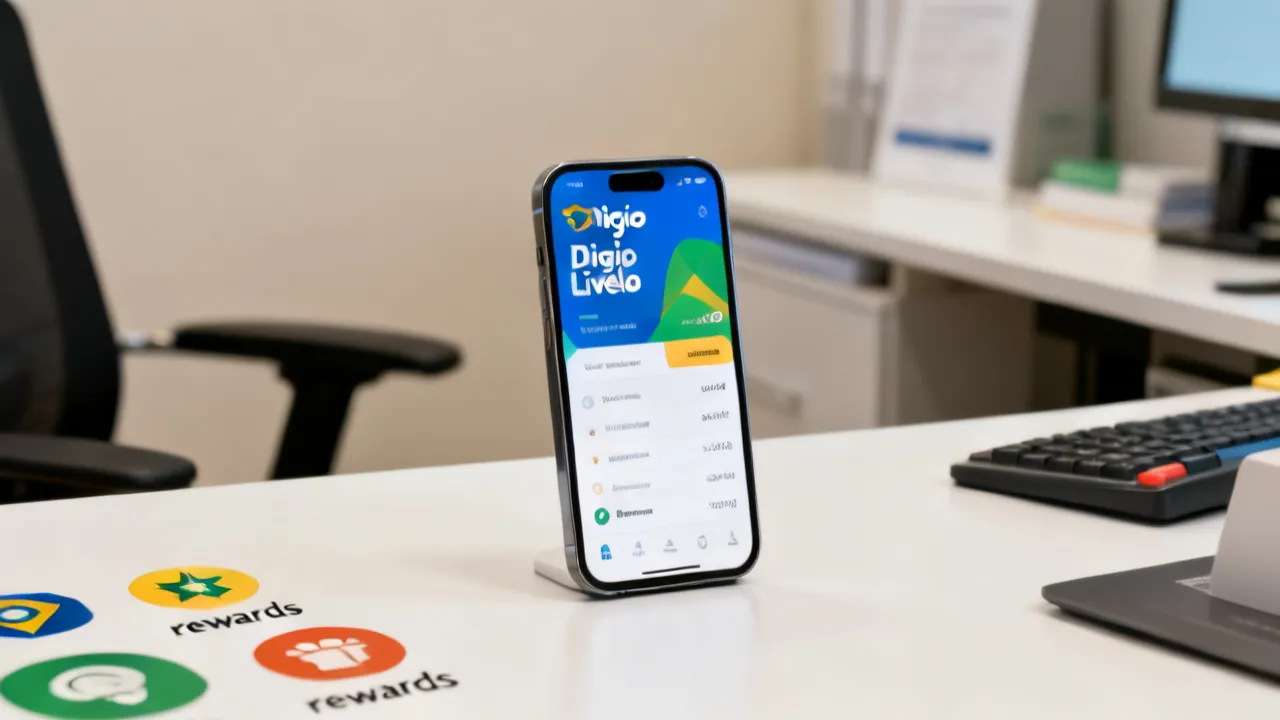
Digio Livelo Explained: Rewards Integration and Use
This guide explains how Digio Livelo works for earning and using rewards, what to verify before you start, and how to choose sensible redemption options. “Digio Livelo” refers to a rewards relationship between Digio’s digital banking/payment experience and Livelo’s loyalty ecosystem. Practically, it’s about matching your spending or engagement to reward accrual, then selecting redemptions that fit your goals.
Receivables Explained with Investopedia Insights and Risk Controls
This guide explains receivables fundamentals and how to manage them with evidence-based controls aligned with Investopedia-style definitions. It provides objective background on what “receivables” means in accounting, why aging matters, and how businesses assess credit exposure, collect payments, and protect cash flow without assumptions.
Accounts Receivable Guide: Investopedia Insights for Clarity
This guide explains how accounts receivable work, how they’re valued and managed, and how firms interpret them in decision-making. Background context covers the Receivables concept referenced by Investopedia, common risks like credit exposure and timing gaps, and the role of policies, documentation, and estimates such as allowances. The focus is practical and objective for analysts and operations leaders.
Receivables: How to Interpret and Manage Credit Risk
Receivables are the lifeblood of many businesses because they represent money owed by customers. This guide explains how receivables are analyzed, why payment terms matter, and how “Receivables Investopedia” concepts help standardize thinking about liquidity and credit risk. Objective background follows, centered on accounting definitions, risk signals, and common management practices.
Bambora Payfac: A Practical Guide for Merchants
Bambora Payfac helps merchants structure card and digital payments through a streamlined payment facilitation model. This objective guide explains what payment facilitation is, how onboarding and compliance typically work, and what merchants should evaluate—pricing transparency, risk controls, settlement timing, and operational responsibilities—so you can choose an approach that fits your business needs.
Understanding Accounts Receivable and Investopedia Insights
This guide explains how accounts receivable work, how to interpret “Receivables” definitions (including perspectives aligned with Investopedia), and how to manage invoice collections with disciplined policies. Accounts receivable refers to money customers owe from credit sales. It sits on the balance sheet as a current asset, and its quality affects cash flow, risk, and working-capital decisions.