This guide explains how to manage Xero Payslip workflows for accurate payslip delivery, approvals, and records. It provides objective background on what payslips represent, how payroll data flows in accounting systems, and why consistent configuration matters for compliance. You’ll also find requirements, implementation steps, and practical FAQs from an expert operations perspective.
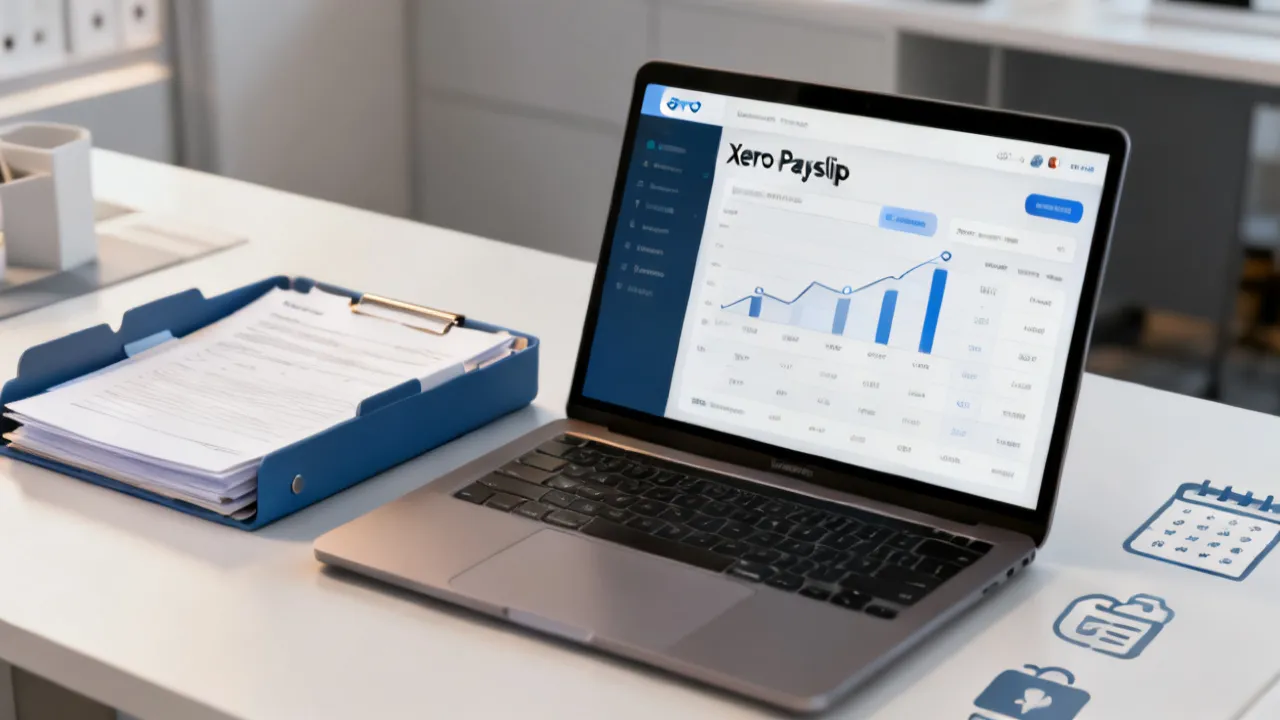
Using Xero Payslip effectively is ultimately about reducing errors in employee pay records while improving traceability for audits and dispute resolution. In practice, the “payslip” is more than a document—it's the formal output that translates payroll inputs (pay rates, allowances, deductions, leave) into a readable breakdown employees can trust. When your Xero payroll configuration and payslip generation rules are aligned, HR, finance, and approvers spend less time chasing mismatches and more time improving payroll governance.
For payroll teams, accuracy is not a purely technical target; it’s an operational requirement with downstream consequences. A small configuration issue—such as a duplicated deduction category, an incorrect eligibility setting, or a leave balance mapping error—can lead to underpayment or overpayment that might not be noticed until employees raise concerns. At that point, payroll may have to re-run calculations, issue corrections, communicate revised values, and reconcile related accounting entries. The cost is rarely limited to time spent correcting the mistake; it can also include employee confidence erosion, managerial frustration, HR workload increases, and audit trail gaps that complicate explanations.
With Xero Payslip, the payslip is typically the moment where payroll “becomes visible.” Until that moment, most inputs and calculations remain behind the scenes. The payslip is the employee-facing artifact, but it is also a control document. If the payslip output is accurate and consistent, it becomes easier to support claims like “this is the basis of your gross pay,” “this is how your deductions were applied,” and “this is the leave activity for the period.” When accuracy is missing, those explanations become subjective and reactive.
Finally, accuracy matters because payroll is a recurring high-impact process. Errors are not only expensive individually; they become more disruptive when they recur. A process that repeatedly outputs wrong values tends to create a “culture of correction,” where each pay cycle becomes a cycle of firefighting rather than a cycle of improvement. Teams that prioritize accuracy early—through configuration, testing, and approval discipline—are typically the teams that scale cleanly during growth, seasonal fluctuations, and policy updates.
In many businesses, a payslip is the employee-facing statement showing how gross pay becomes net pay after deductions. With Xero Payslip functionality, the core goal is to standardize how payroll calculations are captured, reviewed, and issued. While feature names can vary by organization and plan, the common operational elements include: payroll inputs being maintained, pay runs being calculated, payslips being generated per pay period, and records being retained so finance can reconcile accounts afterward.
From an industry standpoint, payroll systems succeed when they create a predictable path from “data entry” to “employee communication.” That predictability is what lets payroll teams manage changes—like new hires, updated bank details, or shifting pay rates—without disrupting the entire pay cycle. In a mature workflow, each pay cycle follows a controlled sequence: update master data, confirm eligibility rules, validate timesheets and allowances, calculate payroll, review outputs, approve, issue payslips, then reconcile and archive.
Additionally, “payslip coverage” is not limited to the visible breakdown of earnings and deductions. Payroll outputs usually feed several interconnected areas:
In well-run environments, the payslip becomes the “single source of truth” for pay period calculations. That doesn’t mean payroll doesn’t keep internal worksheets or payroll journals—it means employees can rely on the payslip as a consistent and traceable summary.
Before teams rely on Xero Payslip for recurring payroll, they should address the underlying conditions that determine output quality. These considerations are rarely glamorous, but they are where payroll accuracy is won or lost:
Even when the software is robust, inconsistent inputs will propagate into the payslip output. Therefore, a good implementation treats payslip generation as the final step of a controlled business process, not a standalone task. This is an important mindset shift for payroll teams: rather than thinking “we configured payslips, so accuracy is assured,” it’s more accurate to think “we built a controlled pipeline that produces payslips from approved inputs.”
Consider also the human side of payroll accuracy. Payroll master data is often maintained by HR systems, spreadsheets, or manual forms. If updates arrive late or are made without the necessary context (for example, pay rate effective dates), the payroll engine will still calculate using whatever it receives. That means your process must ensure that effective dates, eligibility rules, and timesheet information are aligned with policy and contract terms.
Furthermore, governance must include a plan for changes after configuration. Many organizations only test the happy path during implementation. But real payroll issues often occur during change events: promotions, transfers, terminations, unpaid leave, retroactive pay corrections, and policy updates. Your configuration and payslip rules should be tested not just at go-live, but through a change-ready approach where each type of event has a documented method for how payroll should handle it.
If you only do three things to strengthen your Xero Payslip workflow, prioritize these:
This inverted-pyramid focus matters because most payroll errors are predictable and preventable. They are often caused by inconsistent inputs, missing approvals, or insufficient validation between “configured rules” and “actual output.” When those three areas are controlled, the remaining risks become smaller and more manageable.
From an operations and controls perspective, payroll teams typically reduce risk by using a “test-and-verify” approach, especially after changes. Rather than assuming configuration is correct on the first run, expert teams validate the results against known scenarios:
This matters because employees judge payroll trustworthiness by what appears on the payslip. If the output is unclear—or if numbers don’t reconcile internally—payroll disputes can escalate quickly, consuming HR and finance time. Disputes also become harder to resolve when payroll cannot reproduce the logic used to generate the original values. Confidence is built not just by correct output, but by the ability to explain output with evidence.
Expert teams also treat “confidence” as a repeatable outcome, not a one-time achievement. They create a testing regimen that evolves as the business evolves. For example, if the company starts offering a new allowance or introduces a new leave type, the team updates their testing cases and approval rules accordingly. Over time, the payroll organization develops a library of validation checks that help prevent regressions—where a change intended to fix one issue inadvertently breaks another.
In addition, expert teams often implement a “two-view” verification method:
When both views confirm the same results, it’s much easier to identify the root cause of any discrepancy. If payroll view totals look right but finance mapping doesn’t, the issue is likely in account mapping or posting logic. If finance view totals look right but payslip details are wrong, the issue is likely in employee master data or rule eligibility.
You may see references to Xero Payslip pricing and supplier information depending on your region, plan type, and implementation approach. Because subscription pricing can change and varies by plan and procurement route, the safest way to plan is to confirm costs directly with the official supplier channels or your authorized reseller. For internal budgeting, treat pricing as a variable component of the project and document the basis of your estimate (for example, plan tier, add-ons, implementation services, and onboarding support).
Source discipline: if you need to communicate pricing internally, rely on official product pages or written quotes from the relevant supplier organization. Avoid repeating outdated numbers in internal documentation without verification. This discipline is also relevant operationally: payroll projects can fail not only due to configuration errors, but due to incomplete resourcing. If the implementation team underestimates required testing and process documentation time, payslip governance may suffer during go-live.
Even if pricing is outside the direct scope of payslip accuracy, it influences operational readiness. For example, if your budget doesn’t include training or post-implementation support, staff may not understand how to handle exceptions correctly (like retroactive adjustments or eligibility changes). In effect, “pricing decisions” can become “process decisions,” which then affect accuracy outcomes. So the responsible approach is to align budgeting with governance requirements, including testing cycles, approval documentation, and a defined plan for corrections after issuance.
Below is a practical, expert-style rollout sequence. It assumes you want a dependable payslip workflow rather than a rushed setup. Adjust the steps to match your payroll frequency and internal approval structure.
To make these steps more actionable, consider adding internal artifacts at each stage:
These artifacts are not bureaucracy. They reduce the “tribal knowledge” problem where only one person understands how to maintain correctness. Over time, this improves staff continuity and lowers the risk of payroll errors due to staff turnover or system handovers.
This comparison is meant to help you think through governance models around Xero Payslip workflows. It does not replace legal or professional advice, but it can guide internal process design.
| Approach | What It Typically Means | Strengths | Conditions/Requirements |
|---|---|---|---|
| System-led payslip generation | Payslips are generated from configured payroll rules inside your accounting/payroll environment. | Consistent formatting, traceable generation logic, and faster repeats each pay period. | Employee pay data must be maintained accurately; payroll rules must be tested before go-live. |
| Approval-led payslip issuance | Payslips are issued only after designated reviewers sign off on pay run results. | Lower error risk; clearer accountability for changes and corrections. | Clear role assignments; documented approval checkpoints; defined exception pathways. |
| Exception-first workflow | Standard employees can be processed automatically, while exceptions route for review. | Improves throughput; focuses reviewer time where it matters very. | Strong criteria for what counts as an exception; reliable data validation rules. |
| Reconciliation-focused workflow | Output numbers are validated primarily through reconciliation checks after calculation. | Helps prevent month-end surprises; supports audit trails. | Finance must have clear reconciliation templates; mapping must match your chart of accounts logic. |
In many organizations, the “best” governance model is a hybrid. For example, you might generate payslips system-led, but you only issue them after approval-led review for flagged exceptions, while finance performs reconciliation-focused checks to ensure the overall numbers align with accounting expectations. Hybrid designs work well because they combine speed with control, and they reduce the chance that correctness is validated in only one dimension.
When choosing an approach, consider what your organization values most at the time. Early-stage businesses might prioritize throughput and keep controls lean, but still implement basic testing and approval for high-risk changes. Larger organizations may prioritize audit readiness and approvals, even at the cost of more time. The key is consistency: whatever governance model you pick should remain stable across pay periods so employees learn what to expect and payroll teams can improve predictably.
Even with a strong Xero Payslip setup, outcomes depend on internal readiness. Consider the following requirements and conditions before relying on automated payslip output at scale:
These conditions are consistent with standard payroll control principles widely used across finance functions. If you want additional assurance, align your process documentation with your organization’s internal audit framework. In practical terms, internal audit expectations often translate into requirements like: evidence of review, evidence of approvals, evidence of changes, and evidence of resolution for exceptions.
Operational readiness also includes your IT and access controls. Even if your payroll logic is correct, incorrect permissions can undermine accuracy. For instance:
Therefore, align user permissions with governance. Ideally, permissions should follow least-privilege principles: users do what they must to complete their tasks, and approvals happen through defined roles rather than informal overrides.
Another operational condition is “data feed quality.” Many payroll inputs are not created within Xero itself; they arrive from timesheets, attendance systems, HR updates, or spreadsheets. If the timesheet capture method lacks controls (e.g., no validation for negative hours or overtime flags), errors can reach the payroll calculation stage. At minimum, implement checks on timesheet patterns and anomalies before payroll calculation runs.
While the technical mechanics of Xero Payslip are central, the business reason is broader. Payslips serve as an employee record and a transparent communication tool. In many employment contexts, payroll documentation is essential for verifying payments, understanding deductions, and supporting claims or adjustments.
Internationally, regulators and industry bodies emphasize that payroll operations should maintain accuracy, consistency, and traceability. For reference on widely adopted payroll and financial controls concepts, organizations commonly refer to internal control frameworks and accounting governance standards, such as:
For specific compliance requirements (for example, local payslip content, retention rules, or filing obligations), consult official government or payroll compliance resources in your jurisdiction. Even beyond formal compliance, payslip accuracy influences employee behavior: employees can use payslips to reconcile their bank deposits, track overtime earnings, and verify deductions. When the payslip is incorrect, trust deteriorates quickly, and employees may lose confidence in the organization’s payroll competence.
Also consider that payroll is often subject to audit not only for numerical accuracy, but for process integrity. Auditors may ask:
The payslip becomes a key output to support those questions. If your Xero payslip process is governed and documented, it becomes easier to answer audit inquiries with evidence instead of explanation.
Teams often encounter predictable issues. Knowing them upfront helps you design guardrails:
It’s helpful to expand these pitfalls into “why they happen” and “how to prevent them.” For example, inconsistent pay items often happen because different HR staff or business units create similar pay rules independently (or because old pay items remain enabled when policy changes). Prevention requires a centralized catalog of pay items and controlled change management.
Late timesheet submissions happen because managers may not understand cut-off dates, or employees may not know how late adjustments are treated. Prevention requires clear communication of cut-off policies, manager training, and a predictable adjustment process (including how late timesheet hours affect the current vs. next pay period).
Unclear adjustment ownership happens when responsibilities are not explicitly defined. For instance, payroll may correct the inputs once, but no one updates the underlying workflow to prevent recurrence. Prevention involves assigning ownership and requiring root-cause documentation for each correction, especially when corrections happen repeatedly.
Unverified outputs happen when teams become confident too early. A typical pattern is that payroll passes during the first couple of runs, then confidence leads to skipping checks. Prevention involves building validation steps into the routine: even if the team believes configuration is stable, reconciliation and output validation should remain a standard step each pay period.
Weak audit trail discipline happens when teams treat approvals as informal. Prevention includes capturing evidence in the system or in a controlled process tracker, not just in chat messages or personal notes. Audit-ready payroll is often about consistent habit, not about complexity.
To further reduce risk, consider implementing “guardrail alerts” such as threshold checks (e.g., if a deduction is unusually high or if net pay deviates materially from usual amounts). While not all organizations use these alerts, they can be valuable in exception-first workflows.
A Xero Payslip is the employee-facing statement generated from your payroll calculations, showing earnings and deductions for a pay period. Operationally, it also functions as part of your internal audit trail when configuration and approvals are properly maintained.
In many organizations, the payslip becomes the first place employees look when they have questions about their pay. Therefore, the “purpose” extends beyond output generation: it’s about communication clarity, trust, and auditability.
Start with clean employee pay data, apply consistent payroll rules, run a test pay period, and validate outputs through reconciliation logic. Very teams also use an approval workflow so exceptions are reviewed before payslips are released.
To go beyond basic accuracy, add targeted checks: confirm pay period boundaries, validate effective dates, ensure leave balances reflect correct accrual rules, and verify that deductions follow eligibility rules. Also confirm that corrections (if any occur) are applied using a documented method so the system reproduces the corrected outcome reliably.
Typically, the approver is someone responsible for payroll governance (often a payroll manager, HR lead, or finance controller). The key is to define authority, document it, and ensure the approver reviews the right evidence (pay run totals, exceptions, and any adjustments).
Good approval practices include ensuring the approver understands what “normal” looks like and what evidence should trigger deeper review. For example, if a particular department consistently has overtime deviations or a recurring adjustment type, the approval criteria should reflect that reality while still verifying compliance with policy.
Document the cause of the error, identify the corrected inputs, confirm recalculated results, obtain re-approval where required, and retain a record of what changed and why. If payslips were already issued, your process should specify how you re-issue or annotate corrections.
An effective correction process also addresses timing and employee communication. You should define whether corrections are applied in the next pay run as a separate adjustment line, whether a revised payslip is issued immediately, and how employees will be notified. Consistency reduces confusion and helps employees interpret corrections correctly.
Yes. Employee trust often depends on clarity. Ensure the payslip includes understandable pay period dates and a readable breakdown of earnings and deductions. Formatting consistency also supports smoother HR and employee communications.
Formatting also has operational benefits. If payslip line items are unclear or inconsistent, HR staff will spend more time explaining components rather than solving underlying payroll issues. A clear format reduces support workload and helps employees self-serve basic questions.
Use consistent configuration, enforce cut-off dates, apply a structured approval workflow, and ensure payslip outputs reconcile internally. Many disputes are rooted in unclear deductions or mismatched pay items—clean configuration and verification reduce both.
Additionally, reduce disputes by improving employee understanding. If employees understand how overtime is calculated, when leave is deducted, and how deductions are applied, fewer disputes escalate. While you may not be able to change all employee-facing policies quickly, clarity on payslip content and HR explanations can prevent many “misunderstanding” disputes from becoming “accuracy” disputes.
Pricing and supplier terms influence budgeting and project planning, but they don’t determine payroll correctness. For responsible planning, verify pricing details with official supplier channels or written quotes and keep those documents as part of your implementation records.
However, pricing affects resourcing. If a project is underfunded, testing and training may be rushed, which can impact accuracy indirectly. Therefore, connect budget decisions to governance deliverables: testing time, approval workflow documentation, and post-go-live monitoring.
At minimum: verified employee pay data, tested payroll rules, a defined approval and correction workflow, validated reconciliation logic, and a record retention approach so you can reproduce pay run context later.
You should also ensure that business users know what to do when something changes. For example, if a pay rate change comes after the cut-off date, who processes it? When is it applied? How is it documented? These “operational conditions” often determine whether go-live is smooth or chaotic.
Yes, automation is often beneficial when exception criteria are well defined. Expert teams commonly automate standard cases but route deviations (like mid-cycle pay rate changes or unusual deductions) to human review.
Automation is not a substitute for governance. It should be built around controlled rules and thresholds. If your business uses automation, ensure that exception routing is reliable and that reviewers receive enough detail to make decisions quickly.
Implementation timelines vary based on complexity (number of employees, payroll frequency, pay items, and existing data quality). A responsible approach is to estimate based on your data readiness and planned testing/approval stages rather than relying on generic durations.
For payslip accuracy, the critical factor is not calendar time but readiness. A longer implementation that includes thorough testing and approval rehearsal is usually better than a short timeline that risks rework. Payroll is one of the few business processes where mistakes can be immediately visible on pay day, making “speed over accuracy” a risky trade-off.
A Xero Payslip rollout is very successful when it becomes a shared workflow across functions. Payroll, HR, and finance should align on how data is collected, how changes are approved, and how payslips are communicated.
To support alignment:
To make alignment tangible, implement joint “pre-pay run” meetings or check-ins. These don’t need to be lengthy; a structured agenda can be enough. For example:
This coordination reduces the chance that payroll receives incomplete or late information. It also helps finance prepare for reconciliation and HR prepare for employee questions.
When organizations implement Xero Payslip thoughtfully, payslips become a dependable output of a controlled payroll process. The technology matters, but the outcomes depend more on governance: clean input data, disciplined approvals, reconciliation validation, and consistent exception handling.
If you build your process around those fundamentals, you’ll not only improve accuracy and audit readiness—you’ll also reduce the friction that often accompanies payroll changes, especially during periods of growth or policy updates.
As payroll teams mature their Xero Payslip workflows, they tend to discover that the biggest improvements come from consistent habits: validating inputs, rehearsing exceptions, keeping evidence, and making approvals meaningful. Over time, the payslip becomes less of a reactive artifact and more of a reliable control output that employees and auditors can both trust.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

The Guide to Car Trading

Unveiling RS Sul Telecom Services
RS Sul Telecom emerges as a prominent entity in the telecommunications industry, providing reliable services across various regions. This article delves into the offerings of RS Sul Telecom, the benefits it presents to both individual and business clients, and its impact on the modern telecom landscape.
Understanding Rlock Advpl in Business
Rlock Advpl represents a pivotal advancement in business software solutions, offering enhanced security and efficiency for enterprise resource planning systems. This article delves into the intricacies of Rlock Advpl, its application in modern businesses, and the benefits it offers in streamlining operations and safeguarding data. As an expert tool, Rlock Advpl is essential for businesses looking to optimize their IT infrastructure.
Unveiling Atranet Innovation
Atranet represents a cutting-edge concept in networking technology. Harnessing its capabilities can transform digital communication by providing seamless connectivity. Designed to optimize data transfer, security, and efficiency, Atranet is shaping the future of how we connect and share information. This article delves into its structure, applications, and potential impacts on industry practices and consumer experiences.
Understanding Polysulfide Adhesive Applications
This comprehensive guide explores the applications and benefits of polysulfide adhesive, highlighting its unique properties and widespread use in construction, aerospace, and automotive industries. Known for its flexibility and resistance to various environmental factors, polysulfide adhesive is a key component in sealing and bonding applications, providing durability and reliability in demanding conditions.
Comparing Vtex with Salesforce Commerce
This article provides an in-depth comparison between Vtex and Salesforce Commerce, two leading digital commerce platforms. Each offers unique features suited to different business needs. Vtex is renowned for its collaborative commerce approach, while Salesforce Commerce shines with its comprehensive customer relationship management capabilities. Explore their differences, strengths, and insights from industry experts.
Understanding the Latest Chrome Version
This article delves into the intricacies and features of the latest Chrome version. Chrome, developed by Google, is one of the very popular web browsers globally, known for its speed, simplicity, and security features. Each update aims to enhance user experience through improved functionality and performance. Understanding these updates is crucial for both everyday users and developers.
