This guide explains how AvidXchange supports QuickBooks workflows to improve invoice processing, approval routing, and accounts payable visibility. Objectively, the article reviews what these platforms do, how integrations typically fit into an AP team’s controls, and what organizations should evaluate for security, data mapping, and operational readiness.
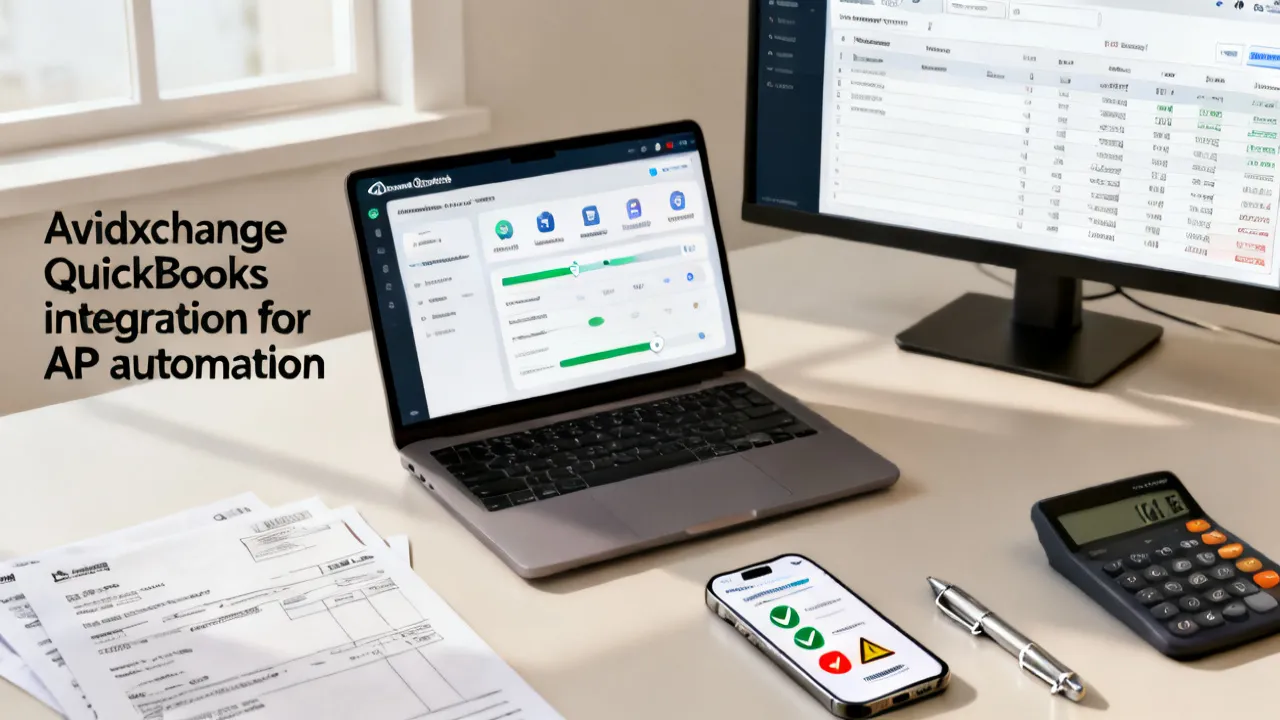
Organizations often adopt AvidXchange QuickBooks integration when they want to reduce invoice handling friction while keeping accounting records consistent in QuickBooks. From an industry perspective, the very important goal isn’t “automation for automation’s sake,” but a reliable workflow that improves visibility, enforces approval policies, and keeps finance data synchronized with the system of record. This guide provides an objective, practical framework for evaluating how the integration supports accounts payable (AP) operations and what conditions typically need to be in place for the process to work smoothly.
When the integration is implemented well, it doesn’t just speed up invoice routing. It also changes how internal controls are demonstrated. Instead of relying on scattered email approvals, manual spreadsheets, or inconsistent documentation, the workflow layer can become the place where approvals are recorded and verified. At the same time, QuickBooks remains the system of record where financial reporting and reconciliations occur. The “alignment” between these two systems—operational evidence in the workflow and authoritative accounting treatment in QuickBooks—is where most organizations either gain major efficiencies or encounter avoidable rework.
AvidXchange is commonly positioned as a business-to-enterprise accounts payable automation platform. In practical terms, it tends to help teams manage invoices through digital intake, routing/approval workflows, and structured payment-related stages—aiming to reduce manual touchpoints such as re-keying invoice details or searching email threads for approvals.
A key way to view AvidXchange is as an operational workflow engine. In a mature deployment, it standardizes how invoices enter the process, how data fields are validated, how approvers receive work, and how decisions (approved/rejected/needs info) are captured. It also provides a consistent mechanism for attaching invoice documentation and tracking the workflow history.
QuickBooks, by contrast, is widely used as an accounting system where books, ledgers, and financial statements are produced. It is very valuable when it accurately reflects the organization’s financial position and supports consistent reporting. Many finance teams care about QuickBooks not only for day-to-day bookkeeping but also because it becomes the reference point for reconciliations and audit trails.
In the QuickBooks environment, the integrity of the data matters: vendor balances, expense accounts, tax treatment, and timing all influence financial reporting. If QuickBooks is updated in a way that does not match the operational reality of approvals or invoice coding, finance teams may spend time performing manual corrections, creating journals, or investigating mismatches.
When people mention AvidXchange QuickBooks in the same breath, they usually mean the operational bridge between (1) how invoices are handled during the AP workflow and (2) how resulting accounting entries, statuses, and documentation land inside QuickBooks.
From an expert operations standpoint, AP automation and accounting integration are tightly linked to internal controls. The integration is very effective when it supports:
It’s also helpful to think in terms of “control objectives.” In AP, organizations commonly care about objectives such as authorization (only approved invoices are paid), accuracy (invoices are recorded correctly), completeness (all relevant invoices are captured), and timeliness (invoices are recorded in the correct period). A well-aligned integration supports these objectives by ensuring the invoice’s lifecycle is captured end-to-end and that QuickBooks reflects the authorized outcomes.
In practical terms, you want the integration to reduce not only the number of manual tasks, but also the number of control exceptions that slip through the cracks. For instance, if coding is inconsistent or approval logic isn’t aligned, invoices might appear in QuickBooks with incorrect accounts or without a clear trail showing who authorized the spend. That can create audit risk and operational drag.
If you’re considering AvidXchange Quickbooks for AP improvements, the very critical decision points are usually not “Will it integrate?” but rather:
In other words, the highest-value evaluation work happens before you run “real” invoices through the setup. The technical integration can succeed, but the business outcome can still fail if mapping rules are brittle, vendor master data is inconsistent, approval states do not match posting logic, or exception processes are unclear.
When finance leaders talk about “readiness,” they often mean these operational and governance assumptions are true: the business has defined where data comes from, who owns it, what happens when it’s wrong, and how the accounting system interprets it.
Many AP leaders pursue AP automation to reduce cycle time, lower operational burden, and strengthen consistency. With an accounting integration in place, teams often look for improvements such as fewer duplicate entries, reduced re-keying, and clearer status tracking. Still, integration success depends heavily on implementation details.
Common benefits teams report (qualitative patterns):
Common friction points to plan for:
It’s especially common for teams to underestimate how often invoices arrive in “non-standard” forms. Even when vendors send invoices in similar formats, real-world invoices can include inconsistent invoice numbers, missing PO references, mixed tax treatments, ambiguous department names, or line items that don’t neatly align to expected categories. The integration can help manage this chaos, but only if the workflow and mapping rules have been designed around real patterns—not only ideal samples.
An integration is only as reliable as the operational and data assumptions behind it. “Good” typically includes well-defined vendor setup, a stable chart of accounts, and clear approval rules. It also includes governance around invoice coding and review thresholds.
Even when the integration is technically supported, organizations should confirm that the workflow layer (where invoices are processed) and the accounting layer (where entries are recorded) share a coherent model of vendors, coding fields, and posting triggers.
To make this more concrete, “good” usually means you can answer questions such as:
In mature AP organizations, governance isn’t only about rules—it’s also about accountability. Someone owns the mapping configuration. Someone owns vendor master data standards. Someone owns approval policy. Someone owns the exception queues and the resolution process.
Below is an objective comparison of typical pre-integration vs. post-integration patterns. The intent is to help teams anticipate process redesign, not to assume identical outcomes across every organization.
| AP Process Step | Before Integration (Typical) | After AvidXchange + QuickBooks Integration (Typical) |
|---|---|---|
| Invoice intake | Emails/PDFs managed manually; variable data quality. | Structured digital capture with standardized fields for workflow routing. |
| Approval routing | Approval chains via inboxes, spreadsheets, or ad hoc systems. | Rule-based routing with queues and documented approvals. |
| Accounting handoff | Re-keying or batch entry; risk of transcription errors. | Posting/coding aligned via mappings to QuickBooks fields. |
| Exception management | Issues discovered late; remediation can be slow. | Clear exception paths; quicker identification of missing or mismatched data. |
| Audit trail | Documentation scattered across email, drives, or manual logs. | Workflow history can support audit-ready documentation of approval steps. |
To further illustrate, consider a typical scenario: a vendor sends an invoice to a shared mailbox, and an AP coordinator forwards it to approvers in email. Approvers respond with approvals or comments, and then AP staff re-enter the invoice details into accounting. Under that approach, it’s common for approval timestamps, invoice numbers, and coding fields to become misaligned or incomplete.
With AvidXchange connected to QuickBooks, the process can be redesigned so the invoice details are captured once, validated against required fields, and then routed for approval. Once approved, the posting step can be driven by structured mapping. If the invoice is missing required information, it can be routed to an exception queue rather than posted incorrectly. This reduces both operational delays and accounting cleanup.
This section is intentionally practical. While exact steps vary by configuration and organization size, the sequence below reflects the approach many AP transformation programs follow when implementing AvidXchange Quickbooks integration.
At this stage, you should also decide whether you’re optimizing for “straight-through processing” (few exceptions) or for “controlled exception handling” (exceptions are expected but managed quickly). Many teams aim for both, but the implementation plan must be honest about current invoice quality and vendor behavior.
Readiness typically includes verifying that QuickBooks vendor records have stable identifiers and that the naming patterns in invoices align with how vendors are represented in the system. If your vendor master includes duplicates (e.g., “Acme LLC” vs “Acme, Inc.”), the integration may route invoices incorrectly or require frequent manual corrections.
Field mapping is where control and automation meet. For example, you need to specify how invoice dates determine accounting periods, how due dates affect payment scheduling, and how tax fields should be treated (especially for invoices that include VAT/sales tax, mixed tax rates, or tax-exempt scenarios). If your organization requires tax to post to specific accounts, you need a mapping plan that can handle multi-line tax rules.
Approval rules should be designed around policies, not around what is easiest to configure. For example, spend categories may map to departments and GL accounts. If the workflow routes based on department but coding is incomplete, you may need routing based on the PO, vendor, or invoice total. The goal is to ensure approvals occur at the right level and that posting doesn’t happen without authorization.
One of the most overlooked aspects of integration is the reconciliation workflow. Even if the automation is correct most of the time, there will be exceptions. Finance teams need a repeatable approach for validating that QuickBooks postings correspond to approved invoices and that any discrepancies are traced back to the workflow record.
A strong pilot includes not only “happy path” invoices but also invoices that represent known pain: missing PO numbers, unusual tax lines, multiple departments on one invoice, and credit memos. If these scenarios aren’t tested early, they often become problems during go-live when volumes increase.
Training should include “what to do when” scenarios, not only how to click through screens. For example: if the invoice fails vendor matching, who resolves it? If the invoice posts to a suspense account, who clears it? If the wrong department code is selected, how is it corrected and what approval is required?
Monitoring should include both operational and accounting indicators: approval throughput, number of exceptions, time in exception queues, posting error rates, and reconciliation discrepancy frequency. Over time, teams can tune routing thresholds and improve data capture expectations based on observed patterns.
The table below consolidates common evaluation criteria. It is presented without links, as requested. For completeness, it also indicates what to verify. (For any final configuration, consult official product documentation and your implementation partner’s guidance.)
| Decision Area | What to Compare/Verify | Typical Condition/Requirement |
|---|---|---|
| Data mapping | How invoice fields (vendor, dates, amounts, line items) map to QuickBooks entities. | Field formats and identifiers must be consistent; unmapped values must route to a defined exception path. |
| Vendor master controls | Whether vendor setup is maintained centrally and how duplicates are avoided. | Vendor names and IDs follow a governance policy; the COA and vendor list are curated before go-live. |
| Approval workflow | Whether approval outcomes correspond to the correct accounting treatment. | Approval rules are documented and tested against your very common invoice scenarios. |
| Posting and reconciliation | How accounting entries appear in QuickBooks and how discrepancies are handled. | Clear reconciliation steps exist; finance has agreed reports to validate postings. |
| Security and access | Who can edit mappings, approve invoices, and make accounting adjustments. | Role-based access is enabled; changes are controlled and auditable. |
| Pilot readiness | Whether the pilot dataset is representative and stable. | Pilot includes recurring invoices and known edge cases to test exception handling. |
The tables above help you identify major areas. To truly ensure the integration aligns with accounting controls, you should expand each area into “specific checks” that teams can execute. The rest of this section provides deeper guidance, using practical examples of the kinds of issues that frequently arise.
Data mapping is not only about matching field names; it’s about ensuring the same meaning flows end-to-end. For example, an invoice “amount” might be interpreted differently depending on whether the amount includes tax, whether there are discounts, and whether credits or partial charges exist.
Below are specific mapping aspects teams often need to clarify:
One reason mapping often fails is because teams focus on successful mapping for a small sample rather than for the full variety of invoices. For a robust control environment, you want mapping rules that either (a) correctly handle the vast majority of invoices or (b) reliably detect when they cannot and push those cases into an exception state before posting.
Vendor master governance is one of the most critical preconditions for reliable integration outcomes. If vendor setup is inconsistent, the integration may route invoices to the wrong approver, code them incorrectly, or fail to post.
Vendor master controls typically include:
As part of vendor governance, many organizations conduct a vendor cleanup effort before integration. This can include matching vendors to known canonical identifiers, removing duplicates, and setting up standardized vendor codes. If your integration mapping relies on vendor name matching, even minor differences (“Acme Co” vs “ACME Company”) can cause mismatches. The more brittle your matching method, the more exceptions you’ll experience.
From a control standpoint, vendor master failures can be serious because they can lead to incorrect expense attribution and incorrect vendor balances. That’s why organizations that succeed with AvidXchange + QuickBooks treat vendor master governance as a core project deliverable, not an optional refinement.
Approvals are at the heart of internal controls. But approvals are also where operational reality can conflict with accounting intent. For example, if an invoice is approved at a certain threshold, but the system posts to QuickBooks regardless of the approval state, then accounting could reflect unauthorized spend.
Approval workflow alignment typically requires answering these questions:
An effective integration doesn’t only move invoices to QuickBooks—it ensures that the workflow decisions govern whether and how those invoices become accounting records.
It’s also important to consider how approvals are reviewed by finance. Some organizations include finance approvers or auditors at specific stages. If the organization requires segregation of duties (SoD), the workflow and permissions must enforce that separation.
Many organizations discover too late that reconciliation is not just a finance activity—it’s also a systems configuration question. You need to know what QuickBooks outputs should look like for each workflow outcome.
To align with accounting controls, teams often establish a reconciliation playbook that includes:
Even with correct configuration, you should expect some exceptions. The key is that those exceptions are visible and traceable, not hidden behind partial or incorrect postings. If exceptions lead to posting to suspense accounts, the suspense clearing process must be defined.
In a mature control environment, finance teams should be able to answer quickly: “Which invoices are approved but not posted?” and “Which invoices are posted but failed approval?” The integration should support these queries using consistent identifiers and status visibility.
Security and access is often underestimated, yet it directly affects the strength of internal controls. The goal is to ensure that:
A control-friendly security model includes change management and audit trails. For example, if mapping rules are updated after go-live, that change should be logged and ideally reviewed. Similarly, if accounting adjustments are made, there should be documentation and an approval chain for those adjustments.
Teams should also define what happens when someone leaves the organization or changes roles. Access reviews should be part of ongoing governance.
Exception handling is where many integrations prove their value. If exceptions are handled consistently, the integration reduces friction even when not every invoice can be straight-through. If exceptions are unmanaged, the integration can create a new class of operational problems.
Strong exception handling typically includes:
Exception handling also needs to be tested. During pilot, teams should measure how often exceptions occur, whether exceptions route correctly, and how long it takes to resolve each exception type. A successful integration doesn’t eliminate exceptions; it manages them effectively.
Beyond the generic steps, teams benefit from testing scenario-based workflows. Below are common scenarios and the kinds of questions you should answer for each scenario to ensure alignment with QuickBooks controls.
In practice, vendors can resend invoices, or invoices can share invoice numbers across periods or services. If the integration posts duplicates to QuickBooks, it can distort vendor balances and cause duplicate expense recognition.
Questions to answer:
Some organizations allow non-PO invoices, but they may require additional controls such as higher approval thresholds or specific coding rules.
Questions to answer:
Invoices often include multiple line items that map to different departments or cost centers. When approvals differ by spend category, the workflow must route each line appropriately or use a consistent policy for the whole invoice.
Questions to answer:
Credits can reverse expenses, reduce vendor balances, or adjust taxes. They require careful mapping to ensure accounting entries correctly reflect the reversal.
Questions to answer:
Some vendors apply different tax rates across invoice lines, or taxes might appear as a separate summary line.
Questions to answer:
When approvers are absent, organizations may use delegated approvals. Controls must still be enforceable.
Questions to answer:
For multi-currency organizations, mapping can include exchange rate handling and accounting currency constraints.
Questions to answer:
Even when mapping and workflow configuration are correct, success depends on governance and change management. The integration changes daily work. If teams don’t understand the new “control flow,” they may attempt to bypass it.
Change management typically includes:
From an internal controls perspective, governance is also about consistency. If different teams interpret invoice data differently or override workflow states inconsistently, control outcomes may degrade. Therefore, changes to workflow or mapping should go through a structured review process.
While organizations differ, the underlying theme across finance modernization is better control and traceability. For objective grounding on why organizations focus on controls, audit trails, and process governance, consider general guidance published by regulators and standard-setting bodies regarding internal controls and recordkeeping. For example:
These references do not specify any particular vendor integration, but they provide a credible governance lens for evaluating why mapping, approvals, and exception handling matter.
It typically refers to connecting an AP automation workflow (invoice intake, routing, approvals, and related processing) to QuickBooks so that the accounting system reflects approved and processed invoice outcomes with consistent vendor and coding information.
In practice, many organizations configure coding rules and mappings, but not every invoice is identical. The integration should be designed to support both standard cases and exceptions. Organizations should confirm how the workflow handles missing fields, ambiguous vendors, and line-item discrepancies.
It’s also important to define what “handle” means. Some organizations allow the system to default coding and send the invoice to an exception queue if confidence is low. Others stop the workflow entirely until a human provides required coding details. The best choice depends on how the organization manages internal controls and how often invoice variability occurs.
Typically, this involves vendor master governance: standardized vendor records, controlled creation/update processes, and consistent identifier usage. Prior to go-live, teams usually clean vendor data and test edge cases where vendor names differ across invoices.
Preventing duplicates is often an ongoing task, not a one-time project. A mature setup includes onboarding workflows for new vendors, validation checks, and audit trails for changes.
Good implementations define exception states and ownership. In general, rejected or unmatchable invoices should remain clearly tracked in the AP workflow and should not post incorrectly to the accounting system. The organization should document the remediation path and approval/authorization requirements.
In many control frameworks, it’s critical that rejected invoices are not quietly adjusted to force a posting. Instead, the workflow should make it clear that the invoice is not an authorized accounting transaction until the exception is resolved properly.
Usually QuickBooks functions as the accounting system of record for financial statements and reconciliations, while the AP workflow system manages operational invoice status, approvals, and processing steps. The exact responsibilities should be formalized in your implementation plan.
Organizations sometimes blur these responsibilities by relying on QuickBooks statuses as if it were the workflow system. Strong implementations keep workflow decisions in the workflow system while using QuickBooks for accounting outcomes and financial reporting.
Common validations include correct vendor matching, accurate line-item mapping to the chart of accounts, appropriate handling of taxes (where relevant), correct status transitions, and clean reconciliation outputs in QuickBooks. Teams also test failure scenarios to ensure the exception process works end-to-end.
Finance teams should also measure operational metrics during pilot, such as number of exceptions by category, time-to-resolution, and the rate of corrections required in QuickBooks. These metrics often predict whether the program will improve control and efficiency at scale.
Often, organizations configure the workflow to reflect current approval policies. However, workflow tools may encourage clearer thresholds and documented routing rules. The key is to confirm that the workflow approval outcomes align with accounting treatment and internal control requirements.
In some cases, teams discover that their existing approval policies are not consistently enforceable because they were based on email chains and informal practices. AvidXchange implementations frequently require formalizing these policies, which can actually strengthen controls if done thoughtfully.
Yes. Organizations typically need defined roles for AP processors, approvers, and accountants, plus controls around who can edit configuration, mappings, and posting-related settings. Your implementation should include permission testing and an access-review process.
A common best practice is to restrict mapping changes to administrators and require approvals for configuration changes—especially those that impact posting rules or account coding.
Choosing AvidXchange Quickbooks is often a strategic decision to create a dependable path from invoice capture to approved processing and ultimately to accurate accounting records in QuickBooks. The integration’s value grows when organizations treat it as a workflow and control project—not just a technical connection. By focusing on mapping readiness, vendor master governance, approval-rule design, and exception handling, finance and AP teams can build a system that improves clarity, reduces rework, and supports confident reporting.
When alignment exists between workflow states and accounting posting rules, the organization gains a stronger ability to demonstrate authorization, accuracy, and completeness. That alignment also helps reduce “month-end surprises,” because finance can reconcile using clear identifiers and track exceptions before they become accounting problems.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans

Explore the Tranquil Bliss of Idyllic Rural Retreats

How to Make Lasting Memories at Disneyland Attractions

4rkojvsx Technology: Industry Insights and Buying Guide

Affordable Phones and Plans for Seniors

Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!

Discovering Springdale Estates

Unveiling RS Sul Telecom Services

Unveiling RS Sul Telecom Services
RS Sul Telecom emerges as a prominent entity in the telecommunications industry, providing reliable services across various regions. This article delves into the offerings of RS Sul Telecom, the benefits it presents to both individual and business clients, and its impact on the modern telecom landscape.
Understanding Rlock Advpl in Business
Rlock Advpl represents a pivotal advancement in business software solutions, offering enhanced security and efficiency for enterprise resource planning systems. This article delves into the intricacies of Rlock Advpl, its application in modern businesses, and the benefits it offers in streamlining operations and safeguarding data. As an expert tool, Rlock Advpl is essential for businesses looking to optimize their IT infrastructure.
Unveiling Atranet Innovation
Atranet represents a cutting-edge concept in networking technology. Harnessing its capabilities can transform digital communication by providing seamless connectivity. Designed to optimize data transfer, security, and efficiency, Atranet is shaping the future of how we connect and share information. This article delves into its structure, applications, and potential impacts on industry practices and consumer experiences.
Understanding Polysulfide Adhesive Applications
This comprehensive guide explores the applications and benefits of polysulfide adhesive, highlighting its unique properties and widespread use in construction, aerospace, and automotive industries. Known for its flexibility and resistance to various environmental factors, polysulfide adhesive is a key component in sealing and bonding applications, providing durability and reliability in demanding conditions.
Comparing Vtex with Salesforce Commerce
This article provides an in-depth comparison between Vtex and Salesforce Commerce, two leading digital commerce platforms. Each offers unique features suited to different business needs. Vtex is renowned for its collaborative commerce approach, while Salesforce Commerce shines with its comprehensive customer relationship management capabilities. Explore their differences, strengths, and insights from industry experts.
Understanding the Latest Chrome Version
This article delves into the intricacies and features of the latest Chrome version. Chrome, developed by Google, is one of the very popular web browsers globally, known for its speed, simplicity, and security features. Each update aims to enhance user experience through improved functionality and performance. Understanding these updates is crucial for both everyday users and developers.
