This guide explains how to manage an Xero Payslip workflow for accurate pay reporting, smoother payroll processing, and better audit readiness. Background-wise, “payslip” information ties into payroll governance, employee transparency, and local statutory requirements. It also reflects how cloud accounting tools standardize data entry and approvals to reduce errors.
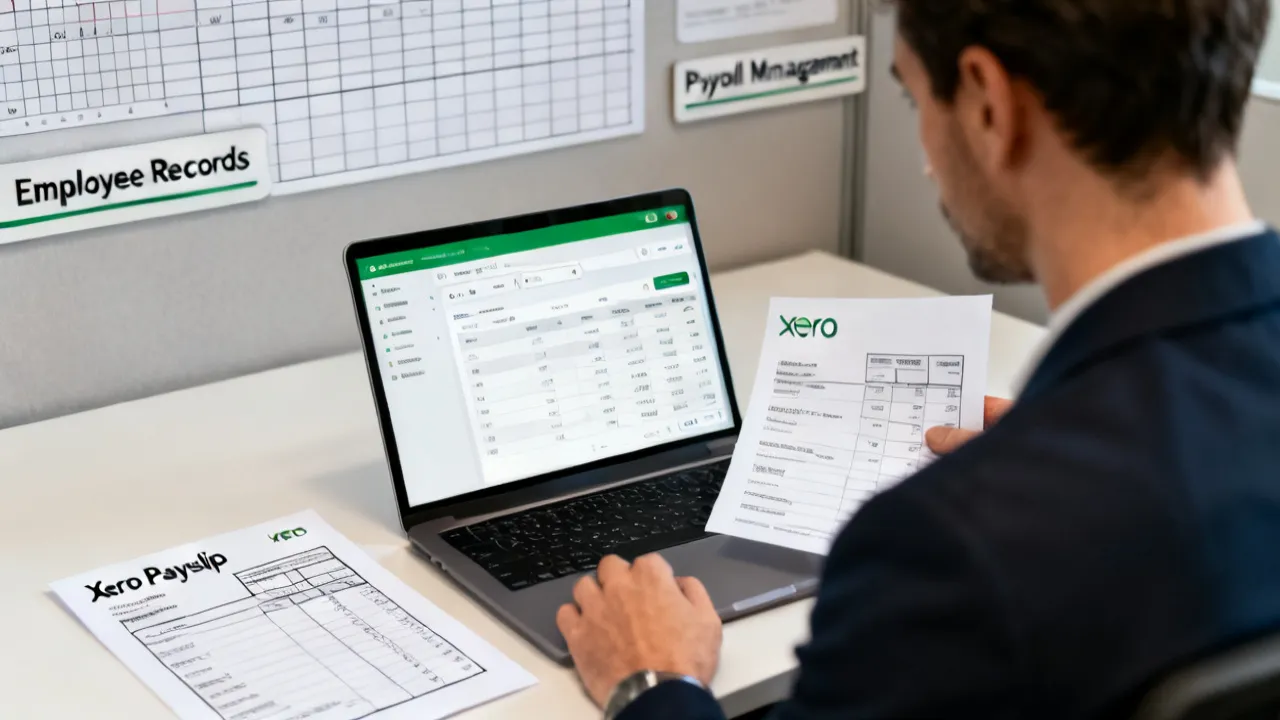
An Xero Payslip workflow should reliably produce clear, employee-ready pay statements while keeping payroll data consistent across payroll runs, accounting journals, and records needed for review. From an industry perspective, the “quality bar” is not simply formatting—it is traceability (who approved what, when), accuracy (gross-to-net logic, deductions, and adjustments), and compliance readiness (the ability to evidence payroll outcomes during an internal review or audit).
If you are using cloud accounting in a small to mid-sized organization, your payroll process usually involves multiple steps: setup, payroll calculations, approvals, payslip delivery, and accounting postings. The more those steps are standardized, the fewer the downstream issues—such as mismatched totals between HR records and accounting reports.
In other words, a payslip workflow is not an “output-only” exercise. It is an end-to-end process design problem. A good workflow ensures that employees can trust what they see, and that finance can defend what happened if questions arise. Those two expectations frequently conflict in everyday reality—payroll needs to be fast, but also provable. The practical aim of an Xero Payslip workflow is to achieve both.
To do this, your workflow must be repeatable. Repeatable means the same control points appear in every pay cycle, with predictable outcomes. It also means that the workflow can handle change—new employees, role changes, benefit elections, arrears, retroactive adjustments, unusual deductions, and last-minute HR updates—without breaking your governance. The best systems are designed so that “normal operations” are easy, but “exceptions” are still controlled.
Finally, because payslips sit at the boundary between operational HR data and the accounting ledger, the workflow should reduce reconciliation burden. Many payroll issues do not show up in payroll processing itself; they show up later at month-end when payroll totals must tie to journals, reports, and statutory figures. Designing for that reconciliation earlier—before payslips are released—is one of the strongest ways to prevent avoidable rework.
Employees typically treat payslips as the authoritative record of what they earned and what was deducted. Employers, meanwhile, use payslips as a governance tool—helping confirm the payroll calculations used for each pay period. When you adopt a structured process around a Xero Payslip output, you are effectively reducing the risk of operational confusion and reconciling payroll outcomes with your accounting system.
In practice, a professional payslip supports:
But payslips do more than explain pay. They become evidence. When employees dispute a component—such as overtime, allowances, or a deduction for a benefit—your ability to demonstrate the inputs and logic used in that pay period is critical. When finance questions the payroll journal totals, your ability to explain how each component contributed to the accounting posting is equally important.
Also consider customer and stakeholder expectations. In many organizations, payroll is part of broader reporting: headcount reporting, cost allocations, internal budgeting, and sometimes project-based billing. If payroll data is inconsistent or poorly documented, downstream teams will struggle to produce reliable reports. A robust Xero Payslip workflow is therefore not just payroll administration—it is part of organizational data integrity.
Another dimension is employee experience. Payslips that are unclear, inconsistent, or missing expected lines generate support tickets and increase manager time. Clear labeling, consistent ordering of earnings/deductions, and stable pay period naming reduce noise. When the payroll workflow is controlled and standardized, employees encounter fewer “why is my pay different?” conversations because the explanation on the payslip is more immediate.
Additionally, because employment law and tax law frequently require recordkeeping, payslips and underlying payroll run data must be retained and retrievable. If your payslip workflow archives in a structured way, it becomes easier to respond to queries from employees, regulators, or auditors. If you rely on ad-hoc copies or spreadsheets with unclear versions, you increase risk and reduce speed of response.
“Xero Payslip” is commonly used as shorthand for the payslip experience and payroll outputs associated with Xero-based accounting workflows. Even when payroll operations are driven through connected payroll functionality, the underlying principle is the same: payslips should reflect the same underlying payroll data that drives postings and reporting. That alignment helps ensure you do not end up with:
In cloud accounting environments, it is tempting to treat payroll as “separate” from the ledger. In reality, payroll is a high-impact data source. It feeds not only the payroll expense but often also balance sheet movements, accruals, liability accounts (for PAYE/VAT-like structures, depending on jurisdiction), and sometimes cost reallocations across departments or projects.
When payslip outputs do not reconcile with ledger postings, you may have to correct entries manually, which can be time-consuming and error-prone. A controlled workflow reduces that by enforcing alignment at the time you calculate and approve payroll.
A useful way to think about your Xero Payslip workflow is as a pipeline:
When each stage is controlled and consistent, Xero-based reporting becomes more trustworthy. When it isn’t, problems can hide until month-end, when the payroll totals must tie back to journals and statutory reporting. That is usually the highest cost time to discover mistakes.
From an expert operations standpoint, you should treat each payslip output as a “controlled document.” Before you issue statements to employees, validate the following:
Confirm that each employee’s profile—tax settings, payment method details, pay frequency, and pay components—is accurate. Many payroll errors originate from incomplete onboarding data or outdated tax/deduction configurations. If your employee list is updated in stages (e.g., HR system first, then payroll), establish a checklist to verify that payroll-relevant fields are current before the pay run.
To make this checklist effective, you should define what “pay setup” means in your organization. For example, pay setup may include:
In practice, employee setup should be validated at two moments: (1) during onboarding/offboarding and (2) before each pay cycle where changes may have occurred. A common failure mode is that payroll is run “successfully” but with outdated settings—so employees receive a payslip that is technically generated but logically wrong. Your workflow should therefore include a pre-run “data readiness” check.
A mature approach also includes change tracking. For example, if an employee’s tax code or deduction start date changes, the workflow should record that change and show who made it and when. That makes it easier to explain what happened if the payslip results differ from what employees expected.
Also consider how you handle new hires and terminations. A payslip workflow should make sure that pro-rating logic is consistent with policy and that termination dates are applied correctly. Employees frequently ask questions about why their final pay differs. If your workflow captures the inputs used (start date, end date, pay frequency, leave/termination status), you can respond accurately.
Make sure the pay period start and end dates match your internal policy and that any timekeeping inputs align with those boundaries. Payslips should not require employees to interpret partial-period logic without explanation.
Pay period boundaries affect more than calculation. They affect how you label payslips, how employees understand the timeframe for earnings and deductions, and how finance accrues and recognizes payroll costs in the correct accounting period.
Operationally, you should define pay period boundaries as a controlled configuration. For example:
A frequent problem is misalignment between time/attendance systems and payroll systems, especially when timezone settings, weekend/holiday processing, or cutover dates are involved. Your workflow should include checks that time entries fall inside the intended pay period window before payroll calculation is finalized. Even if payroll software handles this automatically, you should still verify because exceptions happen.
Another issue is that pay periods may not align with calendar months. Employees sometimes expect month-end summaries to match month-end ledger accruals. If your accounting recognizes payroll costs differently from payroll’s displayed period, you must at least ensure the workflow labels periods clearly and applies consistent rules. This is where a structured Xero Payslip workflow can prevent confusion.
Review the gross-to-net build: base earnings, overtime/allowances (if applicable), statutory deductions, and any discretionary deductions. If your organization uses adjustments (manual corrections), ensure they are labeled clearly and that their reason is captured for later review.
To strengthen this stage, you should move from “reviewing totals” to “reviewing the logic path.” Totals can conceal errors. A workflow that verifies the components and their relationships catches errors earlier.
For example, consider a typical gross-to-net chain:
A robust workflow includes checks such as:
Also consider that employees interpret payslips as story documents. A payslip with multiple adjustment lines but no explanation invites confusion. Therefore, your workflow should enforce description clarity. A label like “Adj” is not enough; employees need meaningful descriptions such as “Correction to overtime hours for PP 01” or “Benefit deduction start—effective 2026-10-01.”
If your organization supports different remuneration types—hourly employees, salaried staff, commission-based roles, contractor-like arrangements—ensure the payslip workflow handles each properly. That might mean different component sets, different deduction behavior, and different approvals.
Finally, remember that pay components must remain stable. If codes or descriptions change between runs without an approved policy change, mapping drift can occur. Drift is one of the most common causes of ledger mismatches. For example, an allowance might be posted to one ledger account based on a code, but a recent configuration change might cause it to post elsewhere—while employees still see “the same” allowance name. A controlled workflow should verify mapping stability.
Even if payment processing occurs through a separate system, the net pay on the payslip should reconcile with your payment file totals (where applicable). A common operational pain point is a mismatch between what employees see and what finance pays.
Payment readiness checks can be partially automated, but they must be validated. Net pay is the point of truth for employees, and any mismatch undermines trust quickly. Your workflow should therefore treat payment reconciliation as a required control step, not a convenience.
Depending on your processes, this reconciliation might include:
Another dimension is timing. Payment files may be created after payroll approvals. If an adjustment is made after file creation, you can end up paying different numbers than what employees were told in payslips. Therefore, your workflow must define “freeze points.” A typical design is: approve payroll results → generate payslips and payment files → perform reconciliation → release. If an exception must happen after freeze, the workflow must require re-generation and re-approval of the affected outputs.
Also consider bank detail updates. If employee bank details are changed close to cutoff, you need validation and an approval path to prevent misdirected payments. A controlled Xero Payslip workflow includes checks that the payment method used for each employee is current and correct as of the pay run effective date.
A robust Xero Payslip process includes documented approvals—who reviewed payroll calculations and who authorized release. Audit readiness improves when your approvals and payroll run history are consistent and retrievable.
Approvals should not be treated as a checkbox. The approval workflow should clearly reflect:
Audit trail quality improves when the workflow prevents “silent changes.” If someone adjusts employee data after a review but before release, you need to record that change and ideally pause the release until the reviewer re-checks impacts. That prevents the scenario where an approved payroll run is altered “just a little,” leading to discrepancies and undermining trust in the control process.
Also consider segregation of duties. At minimum, the person who runs payroll should not be the same person who authorizes payslip release without oversight. If your organization is small and the same person performs multiple roles, you can compensate with stronger documentation, independent review, or additional approvals for high-risk cases.
Finally, approvals should support internal training and continuity. A new payroll admin should be able to look at prior pay cycle approvals and understand the process. If your workflow includes standardized checklists and clear evidence of review, onboarding internal staff becomes easier and less risky.
Organizations that manage payroll consistently tend to implement a few structural habits. These are less about “software tricks” and more about process design.
To make these practices more effective, you can refine them into measurable controls.
Batch by risk becomes more than a scheduling preference when you define risk criteria. For example, employees might be classified as high-risk if they have:
Then your workflow can apply stronger reviews to those employees while allowing lighter checks for low-risk employees, thereby not slowing the whole team.
Exception checks should ideally include several dimensions, not only net pay variance. For example, you can also flag unusual:
These checks can be manual or automated. Even if your organization cannot implement sophisticated automation, a structured set of checks can be performed quickly by someone trained to spot patterns. The key is to define thresholds and document what action to take when exceptions occur.
Standardize coding means you should have a controlled mapping between payroll components and accounting accounts. When a payroll component maps to a ledger account, that mapping should not change informally. If a mapping change is required, the workflow should treat it as a policy change requiring approval.
Document adjustments is often the difference between a manageable issue and a long investigation. If adjustments include only a numeric value with no reason, later reviewers cannot interpret the payroll history. A structured adjustment reason can include fields such as:
Cutoff windows reduce rework. If timekeeping submissions are late, your payroll process may have to either exclude late entries or include them with a correction pass. A good workflow defines which policy applies. It also defines how late entries are handled in terms of approvals and documentation. For example, late times might require manager approval and payroll reviewer approval if they affect overtime or leave balances.
Payroll touches both legal requirements and day-to-day employee trust. The business value of a properly managed payslip is that it becomes an auditable artifact: it captures pay results and supports explanations of earnings and deductions. In many organizations, the accounting function also relies on payroll outputs to produce accurate financial statements.
While specific statutory rules differ by jurisdiction, the general principle is stable worldwide: employers must keep adequate payroll records and provide employees with a clear summary of pay and deductions. For official requirements, consult the relevant government or tax authority publications and your legal advisers.
In addition to statutory compliance, there is operational compliance—your ability to follow internal policy consistently. For example, internal policy might require that:
These are not just “nice-to-haves.” They reduce risk. When organizations experience payroll issues, it is often because controls are informal or undocumented, not because people lack knowledge. A workflow converts knowledge into repeatable actions.
Recordkeeping also includes version control. A payroll run may be recalculated after an error is discovered. If your workflow does not clearly indicate which version was approved and released, you can end up with inconsistent records: employees see the “final” version, while accounting uses an earlier journal. Your workflow should treat versions as first-class objects—track run versions, approvals per version, and outputs generated from that version.
Finally, transparency should not mean “over-sharing.” A good payslip workflow ensures that employees receive relevant pay information without confusing internal operational notes. At the same time, internal audit should have access to the necessary supporting evidence through archived payroll run records.
Below is a practical supplement framed as a comparison table (no links), followed by a step-by-step guide and conditions to meet. This section is designed to help you decide how to structure a Xero Payslip workflow within your existing payroll and accounting operations.
| Stage / Decision Point | Recommended Approach for a Robust Xero Payslip Workflow | What to Verify |
|---|---|---|
| Employee data readiness | Maintain a single source of truth for payroll-relevant employee fields, with clear ownership between HR and finance. | Pay frequency, earning/deduction settings, tax/deduction parameters, employment status changes. |
| Time and attendance inputs | Align timekeeping deadlines to payroll cutoff windows; establish exception handling for late entries. | Hours worked within pay period, approvals for corrections, overtime eligibility rules. |
| Payroll calculation review | Use a checklist and risk-based checks before the payroll run is finalized. | Gross earnings totals, deduction lines, adjustment reasons, net pay logic. |
| Payslip issuance | Issue payslips after approvals, ensuring consistent pay period labeling and clarity of line items. | Pay period dates, line-item descriptions, absence of missing components. |
| Accounting reconciliation | Reconcile payroll results to accounting postings to prevent misalignment between employee and finance reporting. | Journal totals, mapped accounts, timing of accruals or adjustments. |
| Record retention | Archive payslips and payroll run records in a structured manner for future retrieval. | Retention schedule, audit trail completeness, version history. |
Even with a standardized system, a Xero Payslip workflow must satisfy practical and governance conditions:
To make these conditions operational, your workflow should explicitly define how the organization behaves when a condition is not met. For example:
Having these “what happens next” decisions written down reduces indecision under pressure. Payroll often runs close to deadlines; when something goes wrong, the workflow should guide the team rather than rely on improvisation.
Based on recurring patterns seen in payroll operations, these are issues that typically cause employee queries or finance reconciliation delays:
Beyond these, there are additional pitfalls that commonly appear in practice:
Each pitfall typically has a root cause. For example, mapping drift often comes from changes to payroll component setup or accounting integration without governance. Uncontrolled retro adjustments often come from ad-hoc fixes without reason codes or approvals. A well-designed Xero Payslip workflow addresses these root causes by introducing controlled steps, documentation requirements, and evidence capture.
A payslip is read by employees in a personal context; it is audited by finance in a procedural context. The top Xero Payslip implementations balance both.
From an operations viewpoint, that means:
One of the more subtle challenges is that employee interpretations and finance interpretations differ. Employees want explanation of why pay changed. Finance wants reconciliation to ledger postings, correct timing, and controlled evidence. A good workflow ensures that payslip lines match the accounting components used in journals, and that the payslip contains enough descriptors to help employees understand the outcomes—without requiring them to consult finance documents.
To bridge the gap between employee and finance needs, you should define a “minimum viable descriptive” standard for payslip lines. For instance:
When you implement this standard and enforce it via configuration and testing, you reduce both employee queries and internal reconciliation questions.
Finance also benefits when the workflow includes a “component-to-account” verification step. Even in small organizations, component mapping drift can occur. A periodic mapping review—performed perhaps quarterly—helps ensure that payroll components continue to post to the intended accounts. This review can be lightweight but should be documented with evidence, including who performed it and when.
In practice, “Xero Payslip” typically describes the payslip outputs and workflow experience tied to payroll operations within an Xero-based accounting environment. The key point is that payslip details should match the underlying payroll calculations used for accounting and records.
It is worth distinguishing between:
A strong workflow ensures that each of these pieces is aligned and that the workflow preserves the logic chain from inputs to outcomes.
Use a reconciliation step after payroll calculations and before payslip release. Confirm that the payroll totals (gross, deductions, net) map to the same accounts and posting totals used by finance. Maintain consistent pay component coding so mapping does not drift.
To make reconciliation effective, define what “match” means in your organization. For example, you might require that:
If you cannot fully reconcile at the category level, you might reconcile at the totals level and then investigate exceptions. The goal is to reduce unexplained differences to a manageable list.
While specific fields vary by jurisdiction, a strong payslip generally includes employee identification, pay period dates, earnings components, deduction lines, net pay, and relevant notes or reference numbers. The goal is that employees can verify outcomes without needing internal documents.
Beyond these basics, you should also consider including (where your payroll and legal requirements allow):
Be careful not to expose sensitive internal details in employee-facing documents. The workflow should balance clarity with privacy.
Adopt a pre-run checklist, use risk-based review for exceptions, document manual adjustments, and enforce payroll cutoff windows. Separation of duties (review vs. authorization) also reduces the chance of unchecked errors reaching employees.
In addition to these measures, you can reduce mistakes by introducing a “two-step thinking” method:
This two-step approach prevents the common error where teams focus too heavily on the numbers after calculation, while overlooking upstream input changes.
It also helps to maintain a “known issues” log for payroll. If a software feature or integration has a recurring behavior, document how your organization handles it. This prevents repeating the same mistakes pay cycle after pay cycle.
Very organizations benefit from an approval workflow to strengthen governance and audit trail quality. At minimum, establish who runs payroll, who reviews results, and who authorizes payslip release. This supports internal controls and improves confidence during review.
A well-defined approval workflow typically includes:
In smaller organizations, an approval workflow can be simple but must still exist. The goal is not complexity; the goal is that the workflow produces evidence of review and authorization.
Many organizations deliver payslips electronically to support faster access and consistent recordkeeping. The key requirement is that delivery methods comply with your privacy obligations and internal policies, and that the content remains accurate and complete for each pay period.
Electronic delivery introduces its own control needs. For example:
Your workflow should define the re-issue process if an error is discovered after release. Without this, electronic delivery can cause confusion because employees may have downloaded a wrong payslip version.
Follow your correction policy: investigate the payroll run details, assess whether a re-run or adjustment is required, document the cause and corrective action, and communicate with employees according to your internal procedure. Ensure that accounting postings are updated to reflect the corrected payroll totals.
A disciplined correction approach typically includes:
The most important concept is that corrections should be controlled and evidenced just like the original run. “Quick fixes” without documentation can create larger issues during audit or later payroll cycles.
Use official government and tax authority guidance for your jurisdiction, plus reputable professional advisory sources (e.g., certified accountants or payroll consultants). Payroll and payslip requirements can differ, so do not rely on generic templates alone.
A practical way to ensure compliance readiness is to maintain a “compliance checklist” aligned to your jurisdiction. This might include:
Your Xero Payslip workflow should incorporate these compliance requirements as constraints on how you archive, how you label, and how you communicate corrections.
A well-run Xero Payslip workflow is defined by more than presentation—it is defined by controlled inputs, consistent calculation logic, clear employee-facing communication, and strong reconciliation to finance records. When organizations standardize approvals and build repeatable checks into each pay cycle, payroll becomes less error-prone and easier to defend in internal review or audit contexts.
If you approach payslips as structured documents within a governance framework, you get a practical outcome: fewer discrepancies, faster issue resolution, and improved trust between employees and the finance function.
To get there, treat each pay run like a mini project with an evidence trail. Define what “done” means: verified employee setup, validated pay period boundaries, reviewed earnings/deductions logic, reconciled net pay readiness, approved release, reconciled accounting postings, and archived records with complete context. When those elements are present every cycle, your organization builds reliability into payroll rather than relying on heroics.
Over time, as you refine thresholds for exceptions, standardize coding and descriptions, and improve the clarity of adjustment reasons, the workflow becomes faster as well as more accurate. That is the real value: you reduce risk while improving throughput—making payroll both dependable and sustainable.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
The Guide to Car Trading
Understanding the Concept of Ibiaeon
Dive into the groundbreaking concept of Ibiaeon, a theoretical model that combines technological advancements with philosophical perspectives. Ibiaeon represents a unique intersection where innovation meets ethical considerations, aiming to offer sustainable solutions for future societal challenges. This guide presents a deep analysis of the possibilities and implications associated with Ibiaeon.
Understanding the Sage Cte Platform
Sage Cte is a powerful software offering comprehensive solutions for businesses across various industries. This article delves into its capabilities, exploring its integration with different systems, cost implications, and the significance of choosing the right supplier. By understanding Sage Cte, businesses can make informed decisions for optimal operational efficiency and competitive advantage.
An In-Depth Look at Salesforce
Salesforce is a transformative cloud-based customer relationship management (CRM) platform that empowers businesses to streamline their sales, service, and marketing efforts. Known for its robust suite of tools and global reach, Salesforce has become an industry standard in CRM solutions, providing businesses with unparalleled insights and automation capabilities essential for growth and customer retention.
Seamless Integration of Sagepay and Salesforce
This guide highlights the integration of Sagepay with Salesforce, emphasizing the importance of harmonizing payment processing with customer relationship management. Sagepay offers secure online payment solutions, while Salesforce provides comprehensive CRM services, both popular among businesses seeking efficiency. Explore how they complement each other for enhanced business functionality.
Plansource BambooHR: Expert HR Platform Comparison Guide
Plansource BambooHR helps organizations standardize HR workflows with modern recruiting, onboarding, and people analytics. This guide explains what the keywords typically refer to in HR technology contexts, outlines how businesses evaluate these platforms, and provides an expert comparison framework so HR leaders can make informed sourcing decisions based on requirements, implementation scope, and total cost considerations.
Integrating Sagepay with Salesforce
Integrating Sagepay with Salesforce streamlines business operations by combining sophisticated CRM capabilities with a secure payment gateway. This fusion allows businesses to efficiently manage customer relations and transactions within one seamless framework. Sagepay ensures secure and swift payments, while Salesforce aids in comprehensive customer relationship management, enhancing overall operational productivity and customer satisfaction.