This guide explains how Xero Payslip workflows help organizations generate, review, and distribute payslips with stronger controls and clearer audit trails. Objectively, “Xero Payslip” refers to using Xero-based payroll output to structure employee payment records. We then compare common configuration approaches, outline setup steps, and cover essential compliance considerations for employers.
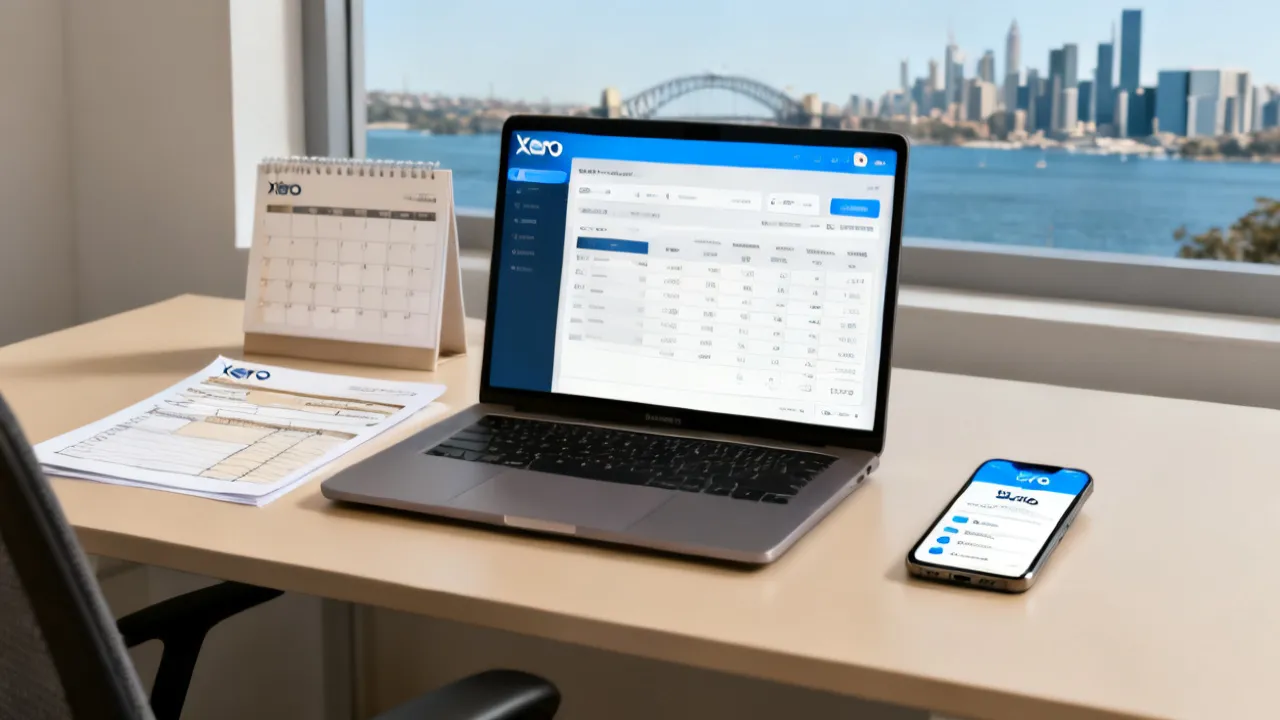
If you manage payroll in Xero, the very important outcome is not merely producing documents—it’s establishing a reliable process for generating, approving, and distributing a Xero Payslip so that employee records remain accurate, traceable, and easy to reconcile. From an industry perspective, the difference between a workable setup and a resilient one comes down to (1) correct pay run configuration, (2) disciplined approvals, (3) secure employee delivery, and (4) documentation that supports internal review and audit needs.
To keep expectations objective: a “Xero Payslip” typically describes the payslip output generated through Xero’s payroll capabilities (or an integrated payroll add-on). In practice, teams treat it as a structured document capturing earnings, deductions, employer contributions, and relevant identifiers for each pay period.
When payroll is handled well, the payslip becomes a dependable record that answers questions quickly: “How much did I earn?”, “What was deducted and why?”, “How does this relate to my leave balances?”, and “What changed since the last pay period?” When payroll is handled poorly, the same document becomes the starting point for disputes, delayed payments, manual work, and avoidable compliance risk.
Therefore, the best mindset for “Xero Payslip” setup is process-first: design how your business will run payroll, then configure Xero (and any integrations) so the configured controls match your actual responsibilities. The goal is not only to make payslips look correct, but to ensure the underlying payroll calculations are correct, the approval path is controlled, and the distribution method does not expose sensitive information.
In many workplaces, the phrase “Xero Payslip” is used to describe three connected items:
From an operational standpoint, this matters because payroll is both a financial process and a compliance obligation. Even when the end output looks simple, the operational chain behind it often includes approvals, policy checks, and reconciliation with accounting journals.
Consider a typical pay period: your workforce may have multiple pay components (regular hours, overtime, allowances, shift differentials, reimbursements, bonuses), and deductions (taxes, retirement contributions, benefits, garnishments, unpaid leave, repayments). Each component can originate from a different source—some from a time system, some from HR updates, some from manual adjustments. A Xero Payslip is where those components converge into a readable narrative and a set of totals.
In day-to-day operations, the payslip functions as both a communication artifact and a governance artifact. Employees use it to validate income; managers may use it to confirm that planned hours and entitlements were applied correctly; finance uses it to connect payroll totals to journals and cost allocations. If any of these stakeholders experience inconsistency—such as a mismatch between expected overtime and what appears on the payslip—the support workload increases and the organization’s trust in payroll decreases.
Payroll systems are used at the intersection of employee relations and financial reporting. That intersection creates real-world requirements:
Professional teams therefore treat a Xero Payslip workflow as a controlled process rather than a “button click.” A reliable process reduces the frequency of rework and, more importantly, reduces the time spent explaining and correcting payroll. In audits—internal or external—teams want to demonstrate that payroll was calculated correctly, approved appropriately, and recorded accurately.
Audit readiness is not just about having “something” to show; it’s about having the right evidence in the right form. For example, it can be helpful to show: (1) the pay run configuration used, (2) the approval logs, (3) the adjustments made after preview, (4) the reconciled totals to accounting accounts, and (5) how you handle employee disputes. Even if audits never occur, this discipline improves operational confidence.
Additionally, payroll issues rarely stay localized. A small error in hours mapping can affect tax calculations, leave balances, or cost allocations. That means accuracy is not simply a “nice to have”; it is a structural requirement that prevents downstream errors in reporting, budgeting, and employee relations.
Organizations typically refine their approach to Xero-based payslips for one or more of these reasons:
In objective terms, the “top” workflow is the one that aligns with your operational maturity and compliance responsibilities—not the one with the very features on paper.
More specifically, many businesses start by focusing on getting payslips to generate correctly, then later realize that payroll needs ongoing governance. Common “refinement moments” include:
In these scenarios, Xero Payslip setup becomes not just a technical task, but a change-management project: teams need clarity on roles, responsibilities, timelines, and how errors are handled.
Experienced payroll administrators and finance controllers often look for a few practical signals of a well-run Xero Payslip approach:
When those elements are present, the payslip becomes a dependable artifact rather than an unstable output.
To add more realism, experts also tend to evaluate “human factors.” For instance:
A successful payslip process is as much about predictable behavior as it is about correct configuration.
Even small configuration choices can change what appears on your Xero Payslip. Key areas to assess include:
Your pay schedule (weekly, fortnightly, monthly) affects how employees perceive consistency and how you manage cut-off times for timesheets and leave submissions. A robust process ensures that pay run “cut-offs” are aligned with how data enters payroll.
Pay run timing is not only about dates on the payslip; it affects calculations and business outcomes. For example, if you close timesheets at 5pm on Friday for a weekly payroll that runs on Monday, your team may inadvertently miss late submissions or corrections. Those late entries then show up in the wrong pay run, resulting in employees seeing an “unexpected” movement of hours or allowances.
Consider building a simple calendar model that identifies:
When these windows are defined and communicated, fewer corrections are needed, and employee questions decline.
Payslips are only as clear as the mapping between payroll components and how you want them displayed. Industry practice focuses on making components understandable to employees while still maintaining accounting clarity for finance.
Mapping deserves extra attention because it influences both readability and reconciliation. For instance, a “Meal Allowance” may be treated as taxable or non-taxable depending on local rules. If your payslip needs to show “Meal Allowance” but finance needs to allocate it to a specific expense account, you need a consistent method to categorize and label the component.
In practical terms, teams often define:
When mapping is inconsistent, payslips may still balance internally, but employees may misinterpret what was paid or why deductions occurred. That can increase HR workload and raise payroll support tickets.
Incorrect employee identifiers can lead to confusion and complicate record retrieval. Teams typically verify critical fields (employee names, payment identifiers, status dates) before each pay run.
Beyond basic identity checks, experts often look at:
Even if you have an approval flow, identity errors can slip through if they are not checked during preview. A preview process that includes a “spot check” for each employee can dramatically reduce downstream corrections.
It’s common for organizations to implement staged approvals: a payroll preparer runs a “preview,” a reviewer checks variances, and a final approver confirms the pay run. Where possible, changes between preview and approval should be minimized.
Approval workflow should be designed to prevent two failure modes: (1) approvals that happen too late (so problems can’t be fixed in time) and (2) approvals that happen without meaningful review (so errors are approved as “noise”). The goal is informed approval, not mechanical approval.
To implement meaningful approvals, consider a standardized preview package that includes:
When approvals use such a package, the reviewer can quickly identify anomalies, and the final approver can confirm that exceptions were resolved properly.
Employees need timely access. At the same time, confidentiality must be maintained. Your distribution method should meet your organization’s security and privacy requirements.
Distribution is frequently treated as an afterthought, but it becomes critical during onboarding, terminations, and disputes. For example:
A secure distribution approach should include controls such as verified contact details, role-based permissions, and an audit trail for access or downloads (if your portal supports it). Even when using a vendor portal, you should understand how identity verification works and how employees authenticate.
You may encounter references to “price” and “supplier” details when implementing a Xero Payslip workflow—especially if you use additional payroll services, integrations, or compliance add-ons. Because pricing varies by country, company size, and module selection, it’s better to treat any single price figure as an estimate unless it’s backed by a current quote.
In procurement terms, the very reliable evaluation approach is to compare:
If you are assessing a specific supplier, request a written scope and a detailed fee schedule. Avoid assumptions based on marketing summaries alone.
To evaluate responsibly, you should also ask procurement-adjacent questions that affect payslip operations even after the initial go-live:
Often, the cheapest option is not the cheapest in the long run if it increases rework. A payslip workflow is an operational backbone; cost should be viewed relative to reliability, support quality, and risk management.
The table below compares common implementation approaches. It’s designed to help you decide what to refine, not to replace advice from your payroll provider or professional adviser.
| Approach | Top for | Operational strengths | Key risks to manage | Typical conditions/requirements |
|---|---|---|---|---|
| Core Xero payroll output with internal review | Businesses with stable payroll routines and in-house process ownership | Clear internal control, consistent approvals, easier finance reconciliation | Process drift if roles and approvals aren’t enforced | Documented approval steps; consistent employee data hygiene; defined cut-off times |
| Xero payroll with HR/time integrations | Teams with high changes in schedules, leave, or timesheets | Less manual entry, improved data consistency | Integration errors can propagate into payslips | Testing in a staging environment (where available); reconciliation checks; monitoring for sync failures |
| Specialist payroll service plus Xero reporting | Organizations needing expert handling of complexity and compliance nuance | Professional oversight; faster resolution of exceptions | Overreliance without internal understanding can reduce control | Clear responsibilities between your team and the supplier; service-level expectations; access and audit requirements |
| Employee self-service payslip access portal | Organizations aiming to reduce HR administrative workload | Reduced manual distribution; improved employee retrieval | Access and identity issues can create support burden | Verified employee contact details; role permissions; documented privacy practices |
It’s also useful to recognize that “approaches” are rarely mutually exclusive. Many organizations combine internal review, integrations, and employee self-service. The practical requirement is that each component is governed: integrations must be monitored, self-service must be secured, and internal approvals must remain effective.
Because payslip handling intersects with payroll governance and privacy, this article uses objective guidance consistent with generally accepted payroll operations. For compliance and reporting requirements, you should consult your local government or statutory bodies and your professional adviser. For example, many organizations reference payroll and record-keeping expectations published by official regulators and trusted accounting guidance; consult the latest materials in your jurisdiction for up-to-date obligations.
Additionally, the exact fields and capabilities visible in a Xero Payslip can vary depending on your Xero setup, country requirements, and whether you use add-ons or integrations. Always validate what appears on the payslip in your configured environment, using test employees and test pay runs prior to go-live.
Below is a practical, step-by-step guide to help you structure Xero Payslip processes. Adapt the sequence to your internal roles and your payroll schedule.
Start by identifying every data source that affects payroll: employee master data, timesheets or rosters, leave records, allowances, and deductions. The goal is to ensure that what you enter into Xero is controlled and consistent with HR policies.
Mapping inputs may sound obvious, but it’s where many payroll projects uncover hidden risk. For example, payroll may pull from different systems: a roster system for hours, an HR system for employment changes, and spreadsheets for one-off adjustments. Even if the payroll team “usually” reconciles those inputs manually, this introduces a risk of drift. The more sources you have, the more you need a consistent approach to reconcile and validate each source before payslip generation.
In a mature process, mapping inputs results in a clear list that includes:
When you map these elements, you reduce the probability that a pay run is built on incomplete or incorrect source data.
Create clear definitions for each earnings/allowance/deduction item that should appear on the payslip. Industry practice favors naming conventions and category standards that employees recognize and finance can reconcile.
Standardization is particularly important for organizations with multiple managers or multiple HR/payroll administrators. Without standardized definitions, different people may name the same allowance differently or assign it inconsistently, leading to confusion and reconciliation problems.
Standardization also improves employee experience. If “Overtime” always appears in the same way and includes consistent subcomponents (e.g., “Overtime 1.5x” and “Overtime 2x”), employees can self-check more easily. This reduces repetitive support requests.
As part of standardization, you may want to create an internal “pay component library” with:
Once created, this library becomes a training resource and a reference for consistency during staff changes or audits.
Before previewing a pay run, verify critical fields such as employee employment dates, pay rates, and any special conditions (for example, where allowances or deductions vary). This reduces the likelihood of payslip corrections later.
Validation should go beyond checking the obvious. Consider what commonly goes wrong:
To reduce errors, teams often run a “pre-pay checklist” that includes verifying: new hires, changes since last pay run, employees with unusual pay components, employees with negative net pay, and employees with recent employment status changes.
If your business uses role permissions, you can further ensure that employee master data changes are restricted to a specific role. That way, payroll preparers focus on payroll execution, while HR focuses on employee data—maintaining a separation of responsibilities.
Very operational errors become visible during a preview. Use a checklist that focuses on high-impact issues: unusual hours, missing leave, incorrect rates, or unexpected deduction changes. This is where your reviewer role adds the very value.
A preview is not merely a “try it out” step; it’s a structured diagnostic phase. A well-designed variance checklist typically includes:
Preview review should also include checks for formatting and payslip content. Some teams mistakenly focus only on totals, but employees may rely on the narrative detail on the payslip. If fields like pay period dates, gross pay components, or deduction labels are misconfigured, employees may misunderstand their payslip and believe an error occurred. Fixing presentation issues before finalization reduces confusion.
Finally, a preview allows you to confirm that employees you expect to be paid are included, and employees you don’t expect to be paid are excluded (or included only for the correct portion of the period).
Where feasible, separate “prepare” and “approve” responsibilities. If one person prepares and approves, ensure there is a secondary check—especially during periods of staff change or system upgrades.
Segregation of duties is a core internal control concept. In payroll, it matters because payroll involves both financial reporting and sensitive employee data. A single person who can both prepare and finalize payroll without review is more likely to introduce errors that go undetected.
Even for small businesses, there are options that preserve control. For instance:
Segregation should also extend to corrections. If you allow after-pay changes, ensure those changes also follow approval procedures—otherwise your approval controls become meaningless once you allow unilateral modifications.
Check that each Xero Payslip displays the appropriate components and that totals match payroll registers. Pay particular attention to consistent formatting, employee identifiers, and pay period dates.
When verifying payslips, consider both computational accuracy and user comprehension:
In some organizations, a sample verification approach is used for large employee populations (e.g., verify all employees for the first pay run, then after stability, verify all employees with exceptions plus a statistically meaningful sample). However, any payroll workflow involving compliance risk should be careful not to reduce validation beyond acceptable tolerance.
If you use employee self-service, you may also want to ensure that payslips are correctly accessible. This includes testing login flows and verifying that employees can view their payslips without errors.
Ensure payslips are distributed using an approach that aligns with your confidentiality requirements. If you use employee self-service, verify that onboarding and identity verification practices are functioning correctly.
Secure distribution is not just about “sending payslips.” It includes access controls and confidentiality. Best practice distribution considerations include:
Distribution also intersects with support. If payslips are not available immediately, the support volume spikes. A well-designed distribution process includes a fallback method for employees who cannot access the portal (e.g., secure re-sending after verification, or providing a controlled download link through the portal).
Finance teams typically want assurance that payroll totals reconcile to accounting entries. Establish a reconciliation routine that compares totals from payroll to accounting journals for the same period.
Reconciliation ensures that payroll is not only correct from a “payslip view,” but also correct in the accounting ledger. Even when Xero calculates payroll properly, if journal mappings or cost allocation dimensions are misconfigured, your financial statements could become inaccurate.
Reconciliation routines commonly include:
As part of reconciliation, teams may create a reconciliation record template. For each pay period, the reconciliation record can capture: date performed, prepared-by, reviewed-by, totals, variance notes, and sign-off. This becomes a powerful audit artifact.
When corrections are needed, document what changed, why it changed, who approved it, and how it affects the payslip. Avoid “silent edits” that can erode trust in payroll records.
Corrections are inevitable in payroll. What matters is how you correct them. A controlled correction process should establish rules such as:
A practical correction workflow might include these steps:
Finally, a correction process should be monitored. If corrections occur frequently, it often signals a root cause: inconsistent input collection, weak cut-off rules, inadequate training, or integration instability.
Payroll governance improves with regular review. Conduct periodic checks of error rates, common correction reasons, and employee support queries. Use those findings to refine training and configuration.
Retention and continuous review serve both operational and compliance needs. From an operational perspective, reviewing error patterns helps you prevent recurring issues. From an audit perspective, retention helps you demonstrate governance over time.
Consider establishing a monthly or quarterly payroll review meeting with representatives from payroll, HR, and finance. A lightweight agenda can include:
Continuous improvement is where payroll operations mature. After a few cycles, teams can refine their checklists, reduce redundant verification steps, and focus on the areas that historically cause issues. This keeps the process efficient while maintaining control.
Even a well-designed workflow can fail if fundamental requirements are missing. Common conditions include:
To make these requirements actionable, organizations often define “minimum viable controls” that must always be present—even during growth, system upgrades, and staff changes.
Minimum viable controls might include:
If any of these controls are missing, the workflow may still produce payslips, but it may not be robust under stress or compliance scrutiny.
Use a structured preview and variance checklist. Confirm pay rates, hours, leave balances, and deductions before approval. Then verify that payslip totals reconcile to your payroll registers and accounting outcomes for the pay period.
Accuracy is easiest when you treat preview as a formal step with a checklist rather than an informal review. Additionally, accuracy improves when your inputs are clean: standardized component definitions, consistent naming, and clear ownership of time and leave data all reduce the likelihood of calculation errors.
Yes, very organizations standardize what appears on the payslip by aligning payroll component definitions and ensuring consistent configuration. Keep employee-facing labels clear while maintaining accounting-friendly categories for finance reconciliation.
Standardization can include grouping and ordering components logically (e.g., regular earnings first, then allowances, then deductions). Even if two employees have different combinations of components, consistent formatting helps reduce confusion and makes it easier for employees to spot anomalies in future payslips.
Follow a correction workflow: verify the underlying payroll inputs, confirm what changed, obtain approval according to your policy, and reissue the corrected payslip if required by your internal and regulatory obligations. Document the change and communicate clearly.
Employee disputes often come from misunderstandings, not only calculation errors. A good process involves:
Clear communication also reduces repeat queries, because employees learn how payroll works and what data affects their payslip.
The top method balances timeliness, confidentiality, and employee usability. Employee self-service can reduce administrative load, but it must be supported by accurate onboarding and reliable access controls.
In practice, the “top” method depends on your environment. For smaller organizations, a controlled email distribution with verification steps might be acceptable. For larger organizations, a portal is often more scalable. Regardless of the method, you should ensure distribution is traceable and that employees can access historical payslips for the retention period required in your jurisdiction.
Payslips commonly include pay period dates, employee identifiers, earnings (including base pay and relevant allowances), deductions, and totals. The exact fields depend on your configuration and any local payroll requirements.
Some organizations also include year-to-date totals, employer contributions, and tax breakdown components depending on jurisdiction and payroll configuration. If employees often ask about deductions, ensuring the payslip includes transparent deduction labels can reduce support.
Ask for a written scope and fee schedule. Compare what’s included in implementation, support, training, and ongoing maintenance. Pricing should be evaluated alongside integration coverage, security controls, and the quality of support for payroll exceptions.
When comparing vendors, also consider indirect costs: onboarding time for HR/payroll staff, effort required to fix integration issues, the time lost to employee support due to portal problems, and any risk of delayed payroll runs. A vendor with better monitoring and faster incident response may reduce these indirect costs substantially.
Segregation of duties (or equivalent checks), logged approvals, restricted access for payroll finalization, and a documented correction policy are typically the very important controls.
Logged approvals are crucial not only for audits, but also for internal traceability. If a mistake is found later, the organization can quickly determine whether the mistake came from preparation steps, configuration issues, reviewer approvals, or finalization changes. This speeds up root cause analysis and reduces repeated mistakes.
For compliance, consult your local statutory and regulatory bodies and seek advice from qualified professionals. Payroll obligations can vary by jurisdiction and employment arrangements, so rely on current official guidance.
Payroll compliance is not static; tax rates, reporting requirements, and leave entitlements can change. Your Xero setup and payslip content may need periodic updates to stay aligned with regulatory changes. A governance practice that includes periodic compliance checks is recommended.
A Xero Payslip workflow should be treated like any other critical business output: it requires structured inputs, disciplined approvals, and secure distribution. When your process includes clear ownership, preview-based validation, reconciliation routines, and a documented correction method, payslips become reliable for both employees and finance. That reliability is the real value—far more enduring than any single configuration screen or implementation shortcut.
If you want, share your organization size, pay frequency, and whether you’re using time tracking or HR integrations, and I can suggest a tailored Xero Payslip workflow model (roles, checks, and reconciliation points) that fits your operating reality.
In the end, the most resilient “Xero Payslip” setup is the one where people can explain the process clearly. Someone should be able to walk through the workflow and answer: What happens first? Who prepares? Who reviews? When do we lock? How do we correct mistakes? How do we distribute payslips securely? How do we reconcile to accounting? If you can answer those questions confidently, your payslip process is not only functional—it’s dependable.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
The Guide to Car Trading
Understanding the Concept of Ibiaeon
Dive into the groundbreaking concept of Ibiaeon, a theoretical model that combines technological advancements with philosophical perspectives. Ibiaeon represents a unique intersection where innovation meets ethical considerations, aiming to offer sustainable solutions for future societal challenges. This guide presents a deep analysis of the possibilities and implications associated with Ibiaeon.
Understanding the Sage Cte Platform
Sage Cte is a powerful software offering comprehensive solutions for businesses across various industries. This article delves into its capabilities, exploring its integration with different systems, cost implications, and the significance of choosing the right supplier. By understanding Sage Cte, businesses can make informed decisions for optimal operational efficiency and competitive advantage.
An In-Depth Look at Salesforce
Salesforce is a transformative cloud-based customer relationship management (CRM) platform that empowers businesses to streamline their sales, service, and marketing efforts. Known for its robust suite of tools and global reach, Salesforce has become an industry standard in CRM solutions, providing businesses with unparalleled insights and automation capabilities essential for growth and customer retention.
Seamless Integration of Sagepay and Salesforce
This guide highlights the integration of Sagepay with Salesforce, emphasizing the importance of harmonizing payment processing with customer relationship management. Sagepay offers secure online payment solutions, while Salesforce provides comprehensive CRM services, both popular among businesses seeking efficiency. Explore how they complement each other for enhanced business functionality.
Plansource BambooHR: Expert HR Platform Comparison Guide
Plansource BambooHR helps organizations standardize HR workflows with modern recruiting, onboarding, and people analytics. This guide explains what the keywords typically refer to in HR technology contexts, outlines how businesses evaluate these platforms, and provides an expert comparison framework so HR leaders can make informed sourcing decisions based on requirements, implementation scope, and total cost considerations.
Integrating Sagepay with Salesforce
Integrating Sagepay with Salesforce streamlines business operations by combining sophisticated CRM capabilities with a secure payment gateway. This fusion allows businesses to efficiently manage customer relations and transactions within one seamless framework. Sagepay ensures secure and swift payments, while Salesforce aids in comprehensive customer relationship management, enhancing overall operational productivity and customer satisfaction.