Credicard Smiles is a rewards-style credit card program centered on everyday spending and cardmember benefits. This guide explains what such a program typically offers, how to evaluate value versus cost, and what to check before applying. Background context covers how issuer programs, partner networks, and redemption rules shape real outcomes for cardholders.
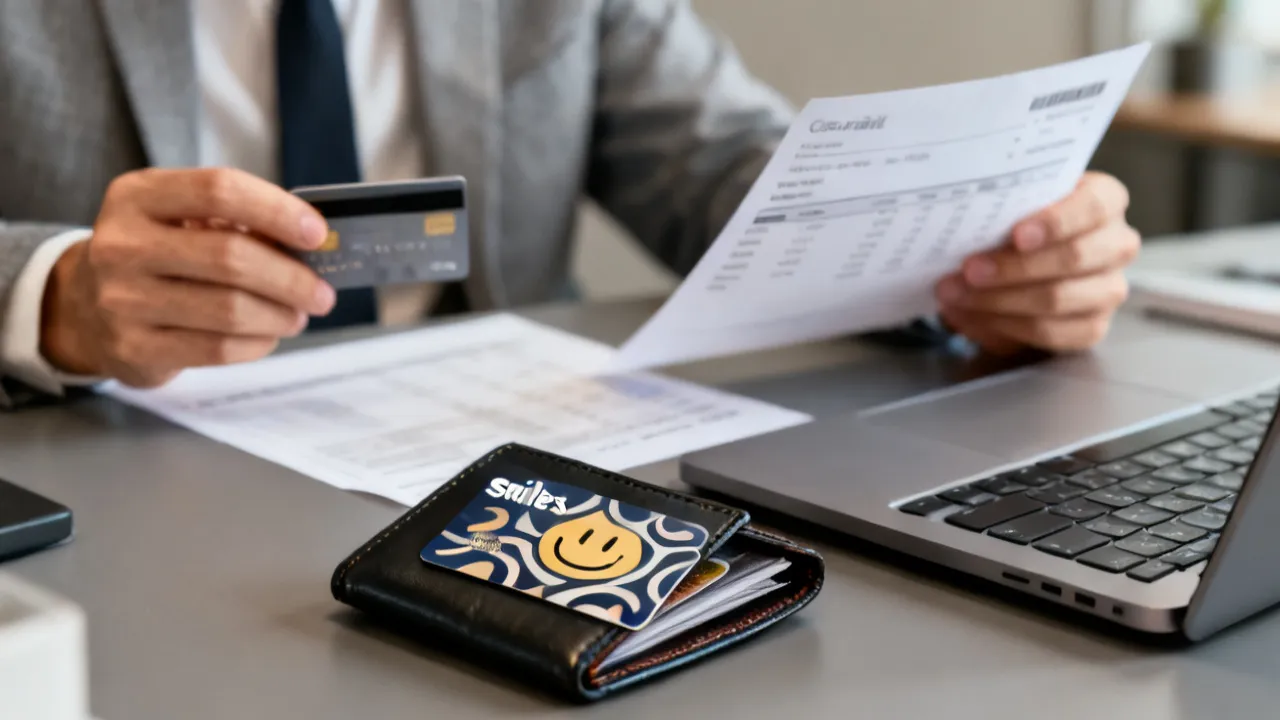
Credicard Smiles is generally understood as a credit card rewards proposition where your purchases can translate into benefits through the program’s defined earning and redemption mechanics. The practical question for cardholders is not whether rewards exist, but whether the structure aligns with your spending habits, your ability to avoid interest charges, and the program rules that govern how points or benefits are calculated and used.
From an industry perspective, rewards credit cards tend to deliver meaningful value only when three conditions hold: (1) you reliably pay on time, (2) your routine spending matches the program’s reward categories, and (3) redemption options are accessible at a favorable effective rate compared with cash alternatives. In other words, Credicard Smiles can be advantageous, but the final outcome depends on contract terms and personal usage patterns.
Because rewards can look impressive at the marketing level while still producing disappointing net value in real life, a careful evaluation matters. “Fit” includes behavioral fit (how you actually spend and pay), mechanical fit (what earns, what doesn’t, and how redemptions work), and logistical fit (how easily you can convert rewards when you want them). When any one of these dimensions is weak—such as you carry a balance, or your purchases fall into excluded categories, or redemption takes effort or offers low conversion—rewards value can shrink fast.
In the end, the best rewards program is the one that you can use consistently without friction and that delivers a net benefit after considering all costs, including opportunity costs. That is why Credicard Smiles should be evaluated like a system, not like a slogan.
Very rewards credit cards—including programs that carry names such as Credicard Smiles—share a core design: you earn “value” based on eligible transactions, and you later exchange that value for items or services offered by the issuer or a partner ecosystem.
However, issuers and program administrators can vary widely in:
Therefore, evaluating Credicard Smiles should begin with the “fine print view”: how the points (or equivalent reward measure) are earned, how they can be redeemed, and what costs can offset reward value (annual fees, interest, and any redemption friction).
Even before you compute anything, you should determine what the “unit of value” actually means. Some programs use points that behave like a currency with a stated conversion rate. Others use vouchers, statement credits, cashback equivalents, discounts off partner pricing, or category-specific reward certificates. The name of the program may remain consistent, but the underlying reward “physics” can change card-to-card and region-to-region.
A common misconception is to treat “points earned” as “value earned.” If redemption rates are uneven—say, points are worth more for travel or less for merchandise—then the true value depends on what you redeem for. Another misconception is to assume reward earnings are stable. Many programs offer promotional multipliers that expire, or they change partner relationships, or they adjust maximum earning caps. That means the best evaluation is forward-looking: can you maintain the spending pattern and redemption choice that produced your expected value?
In practical terms, Credicard Smiles can be advantageous when it functions as a reliable translator between your daily spend and something you actually use—like statement credits, bill pay offsets, travel bookings, or routine shopping discounts. If your redemption preferences don’t match the program’s strongest categories or partners, the value may be lower than it appears.
Because you requested inclusion of price information and supplier details, it’s important to clarify a key issue: your prompt did not provide explicit numbers (such as an annual fee, interest rate, or monthly fee), and I cannot reliably infer current pricing without verified data. For responsible guidance, the top approach is to outline exactly what to look for in the issuer’s published terms and current fee schedule for Credicard Smiles.
Key cost categories to check:
Industry note: credit card reward programs are designed so that the issuer’s economics remain stable. That doesn’t mean you can’t benefit; it means the “value equation” usually assumes responsible usage. Your job as a cardholder is to confirm that your expected net benefit remains positive under real-world fees and spending.
To evaluate costs thoroughly, you should distinguish between:
Interest is the largest behavioral cost most people underestimate. Even if a rewards rate seems strong, the interest rate can overwhelm the reward value. For example, if your net rewards effectively provide a 1–3% benefit but you carry a balance with an APR that is far higher, the interest cost can rapidly exceed the rewards you earn. That is why many consumer education materials emphasize paying statement balances.
Another cost category that can matter is the cost of “cash-like transactions” versus spending. Some rewards programs exclude transactions that resemble cash advances or that are classified as fees, transfers, or money-like operations. If you frequently do money transfers, pay rent via methods that may be treated as cash-like, or use bill pay channels that don’t qualify, you may discover your reward earnings are much lower than expected.
Finally, watch for costs tied to redemption. Some programs require a minimum number of points, or they only allow certain redemption methods that can reduce value. In certain ecosystems, the easiest redemption method may not be the most valuable one. So “cost” is not only what you pay in fees—it is also what you give up when you choose an easy redemption route over a higher-value route.
Your prompt references “supplier details,” which in the credit card rewards context usually translates to the program administrator and partner ecosystem that enables redemption. For Credicard Smiles, think of the “supplier” layer as:
Even if two cards “earn rewards,” the ability to redeem smoothly—without confusing steps or unattractive conversion rates—is often the deciding factor for whether the program feels valuable. When you evaluate Credicard Smiles, prioritize clarity on:
The ecosystem dimension matters because rewards are only useful when you can convert them into the outcomes you care about. In some programs, the best value redemption options are with specific partners—say, certain retail chains, airline booking sites, or digital entertainment providers. If you don’t shop at those partners, you may still redeem, but often at a lower value.
It’s also worth considering how “partner pricing” works. In many loyalty ecosystems, the issuer effectively negotiates discounting or value-sharing with partners. That can produce great deals in partner-specific categories, but it can also mean that the “same purchase” at another merchant doesn’t qualify. Therefore, the value of a rewards program becomes a question of merchant alignment: do you already spend in those partner categories?
Acceptance for earning rewards is usually broader than acceptance for redemption. Your purchases might earn points broadly, but redemption might be constrained to a portal, limited merchants, or specific redemption types. The result can be a mismatch: you may earn rewards quickly but feel blocked or underwhelmed when trying to use them.
To assess the supplier ecosystem, you should examine:
These factors define your real-world “hassle cost,” which can meaningfully change net value—even if the mathematical reward rate looks strong.
An expert approach is to model the program as an income stream with costs. You can do this without complex spreadsheets—just be systematic.
If you find that your estimated net value is thin, you may still use Credicard Smiles for convenience. But if your net value is negative, a cash-back or lower-fee alternative may be more rational.
To apply this method effectively, you may want to separate your spend into buckets. For example:
Then match each bucket to the reward categories under Credicard Smiles. If the program is category-based, your actual value might depend on whether your spending naturally fits those categories. If it is flat-rate, you can estimate more easily, but you should still check exclusions like cash-like transactions or fees.
Next, you should model redemption. This requires an additional step: what is the reward’s “effective rate” given the way you plan to redeem? For example, 10,000 points might equal $100 in statement credit but could equal $70 in merchandise depending on conversion. If you don’t know the conversion, you should find the redemption table in the program’s official guide or portal.
Then incorporate costs. Annual fee is obvious, but also look for conditional fees. Some programs have monthly service charges if you don’t meet minimum spend or if you don’t keep your account in good standing. Others might include costs for premium card services or supplemental cards.
Friction costs are harder to quantify but still important. If redemption requires multiple steps, eligibility checks, or frequent calls to customer support, the “time cost” may be enough to reduce your willingness to redeem. A realistic financial model often treats friction as lowering practical redemption value, because people often redeem later or not at all.
Finally, stress-test. A rewards model should assume at least one year where things don’t go perfectly—like a return/dispute, a partner redemption limitation, or a temporary policy change. You can also test a scenario where your spending shifts away from the program’s best categories. If your net value swings from positive to negative based on such shifts, then your “fit” is fragile, not robust.
Analysts also consider opportunity cost. If you could use a competing card with a simpler redemption (like straightforward cash back) and you already value simplicity, then even a slightly lower mathematical reward rate can be better. “Better” is the program that you consistently convert into value with minimal leakage.
Rewards programs can change over time due to partner contracts, market conditions, and policy updates. Even when Credicard Smiles remains stable in its core structure, details such as conversion rates, redemption availability, and participating partners can shift.
As a result, you should verify:
From a service-design standpoint, the smoothness of redemption workflows matters. Programs that require multiple verification steps or frequent manual assistance can reduce the real value you extract from rewards.
Operational issues often show up in real-world edge cases: refunds, partial returns, split transactions, or disputes. If points are revoked when a merchant refunds a purchase, you should anticipate that behavior and keep it consistent with your redemption timing. For example, if you redeem points right after purchase but later dispute the transaction, you might end up with a negative balance or having to re-earn points.
Expiration and inactivity are another operational concern. Even if rewards “can” be redeemed, an expiration date changes the practical value. A program with a long expiration period might be resilient. A program with short expiration or frequent sweeps of inactive accounts can turn rewards into something you must constantly monitor.
Redemption timing also includes “posting times.” Some rewards accrue immediately, while others post after billing cycles or after transaction clearance. If your redemption requires points to be posted, you might find yourself unable to redeem for purchases you planned to offset. This affects how you plan spending and how quickly you can benefit.
Additionally, some programs offer redemption flexibility only through a specific portal or app. If the portal is slow, poorly designed, or occasionally unavailable, your ability to redeem when you want could be impacted. While those issues might not happen daily, inconsistent availability can harm practical value.
Transfers between accounts, whether to family members or to partner loyalty programs, can add both convenience and complexity. If transfers have fees, minimum amounts, or long processing times, you should incorporate that into your valuation. Transfers can also introduce risk: if partner rules change, transferred points might be subject to new limitations.
Customer support matters because rewards issues are not always easy to resolve by yourself. Missing points, wrong category tagging, or problems when redeeming can occur. A helpful support experience can preserve value, while poor support can increase the effort required to reclaim or correct rewards.
Therefore, operational evaluation should include:
If you can, you can also check user reviews or community discussions for consistent themes—though you should remember that reviews often reflect worst-case experiences more than average outcomes. The goal is to detect persistent operational pain points rather than random one-off failures.
Industry consensus across consumer credit education emphasizes that rewards value is typically outweighed by interest charges when card balances are carried. This is why many financial regulators and consumer agencies stress paying the statement balance to avoid high annual percentage rates (APRs).
Practical requirement: Treat Credicard Smiles as a payments tool first and a rewards tool second. If you can’t reliably pay in full each billing cycle, the economics tend to deteriorate quickly.
Responsible use is not just about interest. It also includes credit utilization management and account behavior that preserves the card’s eligibility status and your ability to earn rewards normally.
Some programs require your account to be in good standing to earn or redeem rewards. If you miss payments, exceed limits, or otherwise create account-level problems, rewards may be suspended. That can create a situation where you “earned” rewards but cannot use them when you need them.
Another consideration is cash advances. Many cards impose separate fee and interest structures for cash advances. Even if the rewards program is generous, cash advances can be treated differently and sometimes do not earn rewards at all. If you rely on cash-like borrowing, your rewards strategy may be undermined.
To maintain the rewards advantage, you can implement a few routines:
It’s also wise to think about refund timing. If you redeem rewards for a desired purchase and then later experience a return, you might lose points or face adjustments. This creates a cycle where your reward “profit” could turn into a correction. Responsible use therefore includes planning your redemption after the purchase clears fully and is less likely to be disputed.
Finally, treat rewards as a bonus on top of good financial hygiene, not a substitute for it. A rewards card can make sense for people who have stable cash flow and who use credit responsibly. For others, the “correct” card may be a low-fee option or a debit-based spending approach where interest risk is eliminated.
The table below is a supplement to help you evaluate Credicard Smiles consistently. It uses neutral categories rather than assuming specific current figures. For exact pricing and rules, consult the latest issuer documentation provided to applicants and cardholders.
| Assessment Item | What to Check for Credicard Smiles | Source Type (Where to Verify) | Step-by-Step Check | Typical Requirement / Condition |
|---|---|---|---|---|
| Annual fee and recurring costs | Confirm whether the card has an annual fee, monthly maintenance fee, or waived conditions. | Issuer fee schedule / product terms | 1) Find the current fee table. 2) Identify any waiver conditions. 3) Note how and when fees post. | Accurate net value depends on your spend level and on-time usage. |
| Reward earning rules | Eligible transaction types, category bonuses, caps, and exclusions. | Rewards program terms | 1) List your monthly spend categories. 2) Map each to reward categories. 3) Check caps or promotional multipliers. | Some transactions (e.g., certain fees or cash-like operations) may not earn. |
| Redemption value | Conversion rates and minimum redemption thresholds. | Rewards redemption guide / partner portal rules | 1) Choose an intended redemption option. 2) Calculate how many rewards are needed. 3) Compare to cash pricing. | Effective value can vary by redemption type and partner pricing. |
| Expiration and reversals | Do rewards expire? Are points removed on refunds/disputes? | Program policy documents | 1) Check reward expiration terms. 2) Note reversal rules. 3) Confirm how refunds affect balances. | Disputes and chargebacks can reduce rewards earned. |
| Payment discipline requirements | Grace period, due date rules, and consequences for late payment. | Account terms and payment schedule | 1) Confirm due date. 2) Set payment reminders. 3) Review late-fee and status consequences. | To preserve value, aim to pay on time and avoid carrying interest. |
| Service availability (supplier layer) | Customer service channel access and redemption support. | Issuer support policy / service-level descriptions | 1) Test redemption steps (if a demo is available). 2) Identify required documentation. 3) Note response channels. | Friction affects your real-world reward experience. |
Credicard Smiles is a credit card rewards program framework in which eligible spending can be converted into rewards or benefits following the issuer’s rules. The precise earning and redemption mechanics depend on the program’s current terms.
Because “rewards program framework” can include many different types of value, it helps to check whether Credicard Smiles is primarily:
Your practical value will depend on which model applies and how you typically redeem.
Estimate your likely annual spend on reward-eligible categories, apply the program’s earning rules to project rewards, then compare the expected redemption value against fees and any likely costs. If you carry balances that incur interest, the program value can quickly decline.
To make this estimation more accurate, you can also:
Not always. Rewards programs typically exclude certain transaction types (for example, fees, cash-like transactions, or specific payment channels). Confirm the eligibility list in the program terms associated with Credicard Smiles.
It can be useful to pay attention to how transactions are coded. Some payments that look like purchases on your statement may still be treated as a different merchant category internally (for instance, certain bill payments, money transfers, or prepaid service loads). If you want to maximize value, it is worth testing a small “borderline” category transaction once and checking whether it earns rewards.
Yes. Rewards programs often adjust partner participation, conversion rates, and redemption availability based on contract renewals and policy updates. Review the latest terms periodically and keep redemption receipts or records when possible.
When rules change, the effect can be uneven: sometimes the earn side changes, sometimes redemption flexibility changes, and sometimes expiration policies change. The most important approach is to ensure you check the specific terms that apply to the time period in which you earned and redeemed.
Very reward systems remove or reduce rewards when a transaction is refunded or reversed. The exact impact depends on the timing and refund policy described in the program terms.
This is also why it is often safer to redeem rewards for a purchase after it has fully settled, especially for high-value redemptions. If your program has strict reversal rules, premature redemption can create a net negative adjustment.
It can, but only if redemption options match your travel plans and if you confirm travel-related fees (such as foreign transaction charges) and earning eligibility. Also consider how quickly you can redeem points when prices change.
Travel fit often includes:
Use the issuer’s official product documentation: the fee schedule, cardholder agreement, and rewards terms linked to Credicard Smiles. Avoid relying on outdated third-party summaries for current pricing.
If you want to verify “current,” check both:
If you’re considering Credicard Smiles, treat the decision as a structured evaluation rather than a marketing comparison. The checklist below is designed to reduce uncertainty:
You can treat this like a “decision gate.” If you can confidently answer each item with a “yes,” the program is likely to be a strong fit. If any item is uncertain—especially redemption feasibility or net cost—then you should investigate further before applying.
One additional “non-negotiable” mindset is to avoid chasing rewards that do not match your behavior. Many people earn a lot of points but redeem poorly, or they redeem reluctantly and let points expire. The best card strategy reduces this leakage.
When consumer organizations and financial regulators evaluate credit card products, a consistent theme emerges: the cost of carrying credit card balances can erode or overwhelm rewards. For readers seeking foundational context, reputable guidance is often found in financial literacy materials published by national regulators and central banking bodies. For example, many jurisdictions publish consumer alerts that emphasize paying statement balances and understanding APR and fees before using reward cards.
Source examples (for background verification): U.S. Federal Reserve consumer guidance on credit and interest cost concepts; and consumer protection resources published by financial regulators and central banks. Use these materials to understand how interest and fees interact with rewards economics.
Note: I’m not asserting specific numerical outcomes for Credicard Smiles because doing so without current, verified program terms and pricing would be unreliable. The correct method is to compute your own effective value using current issuer documentation.
In addition to the “interest dominates rewards” lesson, research often highlights two behavioral patterns:
Both patterns can reduce net value even when the mathematical reward rate is high.
From an industry operations standpoint, reward programs are “ecosystems,” not single features. The issuer’s partners—airlines, retailers, travel platforms, or lifestyle merchants—enable the transformation of reward balances into tangible value. This matters because your perception of value depends on availability and convenience:
As a result, Credicard Smiles should be judged not only on reward earning, but also on the supplier ecosystem’s ability to deliver benefits in the moment you need them.
To make this lens practical, consider three “moments of truth”:
Many programs fail at Moment 2 or 3. They may earn well, but the redemption value is lower than expected, or redemption requires steps that create delay and frustration. When evaluating Credicard Smiles, you should aim to confirm all three moments, at least for the main redemption type you anticipate using.
Another supply-chain factor is the stability of partners. If partners change, the reward value associated with your favorite redemption path can change. This can happen if a partner exits the loyalty program, if pricing changes, or if redemption privileges are reduced.
You did not specify a city or country, and your keyword content included no explicit location. Where programs operate through partner merchants, “nearby” availability can still be relevant: choose redemption partners that match your local shopping and service patterns. If your lifestyle is anchored around frequent purchases at particular merchant types, confirm those categories are eligible under Credicard Smiles. If your redemption is travel-oriented, confirm the travel partners and service channels are accessible in your region.
Localization goes beyond just “can you redeem.” It also includes:
Even if Credicard Smiles is theoretically generous, regional limitations can reduce practical access. Therefore, before deciding, you should check partner availability in your area, especially if your expected redemption is not statement credit (which is usually more universal).
Credicard Smiles can be a sensible rewards credit card option when you understand the earning rules, confirm the total cost structure, and ensure your spending patterns are aligned with eligible categories. Very importantly, responsible payment behavior—especially avoiding interest—determines whether rewards become meaningful value or remain an attractive concept with limited net benefit.
If you want, share the country/region you’re in and the specific Credicard Smiles product terms you’re considering (annual fee, reward earning rates, and redemption options). I can help you compute an effective value estimate using your actual spending profile—without relying on assumptions.
In short, don’t judge Credicard Smiles by the maximum promotional rewards rate alone. Judge it by whether the program reliably converts your actual spending into value you can use—quickly and efficiently—and whether that value remains positive after considering the real costs of the card and the behavior risks associated with credit.
When you treat rewards as a disciplined system, you can enjoy the benefits without falling into the common traps of complexity, overspending, and interest cost leakage.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
The Guide to Car Trading
Maximizing Benefits with Cash Rewards Cards
This comprehensive guide explores the nuances of using Cash Rewards Cards to maximize financial benefits. With a focus on how consumers can harness these cards for cost-efficiency, the article provides an in-depth examination of their functionality, various reward structures, and strategies to optimize their use. Featuring professional insights, the piece serves as a detailed resource for anyone looking to enhance their purchasing power through strategic card usage.
The Comprehensive Guide to Cash Rewards Card
Discover how a Cash Rewards Card can transform your spending habits and financial health. These cards offer users points for money spent, which can be redeemed for cash. Utilizing a rewards card effectively can bring significant benefits, but understanding the terms, fees, and management practices is essential for maximizing rewards and avoiding debt.
Understanding Calcard Sinop for Industrial Supply Decisions
This guide explains how Calcard Sinop fits into industrial procurement decisions, focusing on how buyers compare supplier options, specification compatibility, and delivery reliability. The background sections objectively define what the term typically refers to in supply contexts and why sourcing discipline matters. Readers also get practical criteria for evaluating offers and a detailed FAQ for smoother, risk-aware purchasing.
Calcard Sinop: Industry Overview and Sourcing Guide
Calcard Sinop products are evaluated here as a practical sourcing and compliance guide. The article objectively explains what “Calcard Sinop” commonly refers to in commerce and supply contexts, outlines selection criteria, discusses supplier considerations and procurement conditions, and provides a comparison table, step-by-step checklist, and FAQs to help buyers make defensible decisions.
Calcard Sinop: Buying Guidance and Industry Context
Calcard Sinop products are evaluated here for informed selection, focusing on usage suitability, documentation, and supplier credibility. Then the guide offers an objective background on what “Calcard Sinop” typically refers to in medical supply and product ecosystems, clarifying how professionals compare specifications, compatibility, and traceability across sourcing options.
Calcard Sinop: Expert Guide to Choosing Carefully
This guide helps you evaluate Calcard Sinop options with an objective, expert lens—covering what Calcard Sinop typically implies, how to compare offerings, and what questions to ask before committing. It then explains the practical decision criteria used in the dental/medical supply ecosystem, focusing on quality, documentation, traceability, and supplier accountability.